In my first blog on disclosure reform, I identified three issues that I think should frame the SEC’s project – pretending that the existing disclosure regime doesn’t exist. As I head to CII’s Spring Conference today, let’s tackle the first issue – what is it that investors want? Below you will read (and listen) about an institutional investor survey indicating that most investors skip to specific sections of proxies. And that 6% of investors don’t read them at all. Of course, that number gets much higher if retail investors were included in that survey. And in talking to institutional investors, it might be a lower level staffer who is tasked with reading the proxies as some of the folks on an investor’s proxy committee – all of whom can influence the vote for that investor – that don’t read the proxies at all. Instead, they rely on a short summary from that lower level staffer.
This shows that most investors don’t do a straight read. That makes sense based on my own personal reading habits of SEC filings. But I would posit that different investors value different types of disclosures. That means that “less is not more” as I believe that most investors don’t care about the ultimate length of a disclosure document as they navigate to the sections they want and aren’t concerned with reading the entire thing. This reflects the sentiments expressed by Corp Fin Director Keith Higgins in his recent speech on disclosure reform (ie. reducing volume of disclosure is not the sole end game, particularly given that many investors have expressed an appetite for more information, not less).
So the mission of the SEC’s project shouldn’t be about reducing document size. However, I do imagine that investors want a better reading experience for those sections that they do read – in other words, better usability. That’s one of the reasons I have been highlighting fine examples of usable disclosure in my spate of recent videos about ’14 proxy statements. It might be time for a “Plain English 2.0” campaign by the SEC.
But let’s back up. How important are SEC filings compared to other ways that a company communicates? Earnings calls, investor conferences, interviews with senior executives in the press, other postings on the IR web page and via social media. It’s fair to say that investors care more about those other ways (and of course, neutral third-party analysis is even more valuable – but that doesn’t mean that corporate disclosure isn’t important. Investors and those neutral third parties need info directly from the source too). This touches on the second issue about how disclosure is made available – but I think it’s important to consider why investors might care about communications outside of SEC filings more.
It’s because more forward-looking information might be gleaned in those types of communications. It’s also likely that content is more “straight talk” in nature since its not as “lawyered” as a SEC filing. I believe that if more disclosure made in SEC filings was crafted in the vein of Warren Buffett’s letter to shareholders, it would be consumed by investors more. I know that we all can’t be Warren – but that doesn’t mean we shouldn’t try or be trained to write so.
Anyways, more surveys will be conducted about what investors want to see in disclosure – and the results will be meaningful to guiding disclosure reform. But I also think that big data should play a role here. I don’t want to place too much reliance on the short-term – but studies already show what type of corporate information is most likely to cause the market to move. Some investors might state that they want certain types of information, but their behavior illustrates that they really care about other types.
Finally, consider the medium. I think video will continue to take off as a way to reach investors. Consider this excerpt from this interview with communications expert Nina Eisenman:
So we had the opportunity to interview some buy-side and sell-side analysts about this topic, and most analysts will go directly to the 10-K. The interesting thing that we found in our interviews is that if there is video content, and the video content is not just a reiteration of the content they just read (so it can be something like a virtual investor day by showing new facilities or a new product line) investors are very interested in seeing that type of content. It adds another layer that they couldn’t get from the print.
Investor Survey: Proxy Disclosure Preferences
At our proxy disclosure conference last year, one panel still rings in my mind about how one institutional investor said she might have a staffer spend 20 minutes on a single proxy statement – but then that company might garner a maximum of 5 minutes worth of discussion during the proxy committee meeting when the actual decision is being made to cast votes for the company’s annual meeting. For me, this speaks volumes about how important it is to strategize when deciding on your approach to conveying your story to investors.
Even with the intense focus on improving proxy disclosure, a recent survey of investors from RR Donnelley indicates that few read all the details. 60% responded that they skip directly to specific sections, usually the CD&A executive summary. That, along with the proxy statement summary if one is available, and the CD&A, are considered the key sections. 12% reported they don’t read proxies at all, and only 6% review the entire document.
Disclosure that received high marks includes director nominee information, director independence, corporate governance profiles and company opposition statements to shareholder proposals. While investors also generally liked the discussion of compensation philosophy, they were lukewarm about the clarity of specific compensation disclosure surrounding pay-for-performance alignment and performance measures, which is unfortunate given investors’ sentiments that these areas are two of the most important considerations affecting voting decisions. Director-related disclosure that received poor marks includes succession planning and board evaluations. We note that neither discussion is required by regulation, but has become more common due to investor interest.
While providing graphic presentations for executive compensation is a trend that is clearly favored by investors, respondents complained about graphs that were “over-engineered”, complex and poorly-labeled or simply difficult to follow. Companies should be aware that some investors believe they were being deliberately misled in certain cases.
In terms of presentation, an overwhelming number of investors reported that they view proxies through online platforms rather than reading hard copies. Their own voting policies and analysis, along with direct engagement with the company and a review of proxy statements, are the biggest influences in how they vote. Not surprisingly, investors wish proxies were shorter, preferably under 60 pages.
Podcast: Investor Views on Proxy Disclosure
In this podcast, Ron Schneider discusses RR Donnelley’s recent survey of institutional investors about what really matters to them in proxy statements (here’s a survey summary), including:
– Why did RR Donnelley conduct the survey?
– What was the survey’s methodology, target audience and who responded?
– What were the key results of or lessons learned from the survey?
– What were the most surprising responses to the survey?
– How can companies use the intelligence gleaned from the survey?
Recently, SEC Commissioner Aguilar delivered this speech on “Looking at Corporate Governance from the Investor’s Perspective”…
We are very excited to announce that Corp Fin Director Keith Higgins will be part of our “Annual Proxy Disclosure Conference” on September 29th-30th. Registrations for our popular pair of conferences (combined for one price) – in Las Vegas and via video webcast – are strong and for good reason. Register by this Friday, as rates go up after that!
The full agendas for the Conferences are posted – but the panels include:
– Keith Higgins Speaks: The Latest from the SEC
– Preparing for Pay Ratio Disclosures: How to Gather the Data
– Pay Ratio: What the Compensation Committee Needs to Do Now
– Case Studies: How to Draft Pay Ratio Disclosures
– Pay Ratio: Pointers from In-House
– Navigating ISS & Glass Lewis
– How to Improve Pay-for-Performance Disclosure
– Peer Group Disclosures: The In-House Perspective
– In-House Perspective: Strategies for Effective Solicitations
– Creating Effective Clawbacks (and Disclosures)
– Pledging & Hedging Disclosures
– The Executive Summary
– The Art of Supplemental Materials
– Dealing with the Complexities of Perks
– The Art of Communication
– The Big Kahuna: Your Burning Questions Answered
– The SEC All-Stars
– Hot Topics: 50 Practical Nuggets in 75 Minutes
We continue to post new items regularly on our “Proxy Season Blog” for TheCorporateCounsel.net members. Members can sign up to get that blog pushed out to them via email whenever there is a new entry by simply inputting their email address on the left side of that blog. Here are some of the latest entries:
– Think You Hold “Irrevocable Proxies” to Back Up Voting Agreements with Large Investors/Dissidents? Think Again!
– MD&A Case Addresses Whether an Uncertainty Is “Known”
– Advances in Technology May Impact Segment Reporting
– Shareholder Proposals: Case Involving Statement in Opposition
– An Interview with Vanguard on Shareholder Engagement & More
– Shareholder Proposals: WCN Wins “Proposal by Proxy” Appeals Case
– Update: District Court Denies Motion for Reconsideration in MD&A Case
On Friday, the SEC issued an order of partial stay of its conflict minerals rule (for those portions of the rule that the appellate court held violates the 1st Amendment). Since Corp Fin’s guidance from earlier in the week already gave companies flexibility to not provide disclosure that arguably would violate the 1st Amendment, this formal action by the Commissioners doesn’t add anything new. Perhaps this order and Corp Fin’s guidance were originally supposed to come out at the same time – but then this Commission order was held up because they knew NAM and the other petitioners were going to file a motion for a full stay – which they did on Thursday – and the SEC’s order denies this motion by granting only a partial stay.
This doesn’t mean the battle with NAM, et al is over as they are still fighting this in court with this new emergency motion for stay, looking for a May 26th ruling by the court – as noted in this Akin Gump blog…
We continue to post new items regularly on our “Proxy Season Blog” for TheCorporateCounsel.net members. Members can sign up to get that blog pushed out to them via email whenever there is a new entry by simply inputting their email address on the left side of that blog. Here are some of the latest entries:
– CEO-CFO Certifications: Should Corp Fin Staffers Review Them?
– Shareholder Proposals: Cash Awards for Best Proxy Advisor
– Shareholder Proposals: Stats for This Proxy Season
– Sustainability: SASB & IIRC Agree to Disclosure Standards
– MD&A: Don’t Forget Material Trends and Uncertainties
– Statements in Opposition: Use of Bullets
Good news. Alan Dye just completed the 2014 edition of the popular “Section 16 Forms & Filings Handbook,” with numerous new – and critical – samples included among the thousands of pages of samples. Remember that a new version of the Handbook comes along every 4 years or so – so those with the last edition have one that is dated. The last edition came out in 2009.
Act Now: If you don’t try a ’14 no-risk trial to the “Romeo & Dye Section 16 Annual Service,” we will not be able to mail this invaluable resource to you this month when it’s done being printed. The Annual Service includes a copy of this new Handbook, as well as the annual Deskbook and Quarterly Updates.
Does the SEC Have Authority to Require Disclosure to Further Societal Interests?
A few weeks ago, in the midst of a blog on a different topic, I noted that conflict minerals wasn’t a good idea for the securities law. This led to an interesting email discussion with Adam Kanzer, Domini Social Investments’ General Counsel about what is the purpose (purposes?) of eliciting disclosure from public companies.
Here are Adam’s thoughts on the subject:
Is there a social purpose of the securities laws? Although the original intent was to guard against fraud, that was the problem of the day. If one reads Section 2 of the 34 Act, it seems pretty broad to me. If the capital markets are creating broad societal problems, I think the SEC has authority, as they did with Y2K, and as they do with climate change.
The original enacters of the ’33 and ’34 Acts, of course, were not considering conflict in the Congo or climate change (both of which raise significant social, environmental and economic issues). The point is that the SEC has broad authority to regulate capital market participants to protect the public interest. That’s a broad mandate that they should embrace. According to this study by Steve Lydenberg, the key phrase “necessary or appropriate in the public interest or for the protection of investors” appears in several variations approximately 210 times in the 34 Act.
I find it very hard to accept that the Roosevelt Administration intended to create an agency solely dedicated to the financial interests of the wealthiest Americans, and I strongly suspect that if Brandeis were alive today, he’d recognize his fingerprints on the conflict minerals rule. For more, check out Cynthia Williams’ Harvard Law Review article on the SEC and ESG disclosure. It’s time for the SEC to recapture its original purpose in a world of globalized systemic risks.
Happy Anniversary Baby! 12 Years of Blogging and Counting
Tomorrow marks 12 years of my blither and bother on this blog (note the DealLawyers.com Blog is over 10 years old – not shabby!). It’s one time of the year that I feel entitled to toot my own horn – as it takes stamina and boldness to blog for so long. A hearty “thanks” to all those that read this blog for putting up with my personality. I’m sure I won’t get more refined with age…
Last week, I blogged about a wide-ranging interview with Warren Buffett on CBNC that covered many topics including his decision to abstain in a vote on Coca-Cola’s controversial equity compensation plan, even though he thought it was “excessive.” Here is a transcript of that interview. Warren sat on Coke’s compensation committee for many years – but he left Coke’s board in 2006. Now his son Howard sits on Coke’s board (but not its comp committee).
As reported in this WSJ article yesterday (and here’s a Reuters article), Coke likely will revise its compensation plan before it goes into effect next year, primarily due to Warren’s sentiments. This is pretty remarkable given that the plan received 83% support from shareholders at Coke’s annual meeting last week. Here is an excerpt from the WSJ article:
Mr. Buffett aired his reservations about the plan privately in recent weeks to Coke Chief Executive Muhtar Kent in three conversations, including at a dinner in Mr. Buffett’s hometown of Omaha, Neb., according to some of the people familiar with the matter. Mr. Buffett’s conglomerate, Berkshire Hathaway Inc., is Coke’s largest holder of stock in the company, owning 9% of the beverage giant’s shares.
Mr. Buffett has frequently expressed his distaste for pay plans that rely heavily on stock options, calling them “lottery tickets” for executives that often generate outsize rewards. Such options give the recipient the right to purchase shares at a later date for a set price. On Wednesday, Mr. Buffett said he has been clear with Coke management from the outset that he thought the plan was excessive. “I’m against the plan, and they know it,” Mr. Buffett said in an interview with The Wall Street Journal.
Cap’n Cashbags: Passing on Stock Tips
In this 30-second video, Cap’n Cashbags – a CEO – passing on a stock tip to earn a little extra money. The digested napkin parrots the fact pattern from a recent SEC enforcement action against a broker and law firm clerk (here’s the SEC’s complaint against them):
Our May Eminders is Posted!
We have posted the May issue of our complimentary monthly email newsletter. Sign up today to receive it by simply inputting your email address!
Yesterday, during a House Financial Services Committee hearing about the SEC’s budget, SEC Chair White said that the SEC will continue to implement the bulk of its conflict minerals rule despite the recent ruling by the US Court of Appeals for the DC Circuit (here’s her written testimony – which doesn’t include this statement). Not a surprise given the joint statement from the Republican Commissioners urging a full stay as I blogged yesterday. That was a failed preemptive plea. But still no word whether the SEC will seek a rehearing, etc.
Then in the early evening, Corp Fin issued interpretive guidance, coming in the form of a statement from Corp Fin Director Keith Higgins. The statement notes:
– June 2nd Deadline Remains the Same – Companies are still required to file initial Form SDs by June 2nd.
– No Need to Label – The big change is that – in line with the appellate decision – companies aren’t required to characterize any products as “DRC conflict free” if they have not been found to be “DRC conflict free” or “DRC conflict undeterminable.” My guess is that most companies will decide to drop the label until this court wrangling gets sorted out, particularly if the label isn’t important to a company’s due diligence discussion or its plans going forward.
– Requisite Disclosures – For products that otherwise would have merited a label other than “DRC conflict free,” disclosure is required for the facilities used to produce the conflict minerals, country of origin and efforts to determine the mine or location of origin.
– Need Audit If Voluntarily Label – For those that voluntarily decide to use “DRC conflict free” label, they must obtain a private sector audit (but no audit required if no products identified as “DRC conflict free”).
The SEC’s Internal Battle Over WKSI Waivers: Are Some Companies “Too Big to Bar”?
Yesterday, I blogged that Democratic Commissioner Kara Stein had dissented on a WKSI waiver. This was a waiver granted to the Royal Bank of Scotland Group, whose subsidiary was criminally convicted for its conduct in manipulating LIBOR. Kara notes that “since the inception of WKSI nearly a decade ago, the Commission had not granted a WKSI waiver for criminal misconduct” until one instance last fall and then this case. She also fears “that the Commission’s action to waive our own automatic disqualification provisions arising from RBS’s criminal misconduct may have enshrined a new policy—that some firms are just too big to bar.” Here’s a Bloomberg article that notes that Commissioner Aguilar also voted against – while Chair White and Commissioners Gallagher and Piwowar voted in favor (and here’s another piece).
Yesterday afternoon, Commissioner Gallagher issued a statement on WKSI waivers that explains his approach to them. Essentially, he is against a “punishment-based view” (here’s a Reuters’ article about his statement). Here is an excerpt from his statement:
Philosophically, the punishment-focused view of WKSI waivers is even more troubling. I am not proposing to ignore the severity or gravity of criminal misconduct. These types of violations are serious, and should be treated as such. But the misconduct itself is appropriately punished through the underlying criminal or civil enforcement process. It is only when that process has been exhausted, and the entity appropriately punished, that we turn to the question of whether the collateral consequence of that punishment—the loss of WKSI status—should be waived. The question of whether to grant a WKSI waiver is, or at least used to be, a dispassionate analysis, undertaken by the technical experts in the Division of Corporation Finance, separate and apart from the enforcement process.
How the Supreme Court’s Lawson Case Impacts Public Companies
In this podcast, Steve Pearlman of Proskauer addresses whistleblower protections in the context of the recent Supreme Court decision – Lawson v. FMR – and the implications for both public and private companies (here are memos on that case), including:
– Can you describe the Majority’s ruling and the reasoning it used to reach that result?
– Are there any particular risks for employers that this ruling creates?
– What types of new claims should we expect to see as a result of this ruling?
– How does this ruling affect public companies, and what should they do?
“Nobody told me there’d be days like these. Strange days indeed – strange days indeed.” John Lennon’s words, but they apply to yesterday’s news out of the SEC. First, the two Republican Commissioners – Michael Piwowar & Dan Gallagher – issued this joint statement on the conflict minerals court decision. This prompt many members to assume this means that these two lost their argument and that the SEC is not issuing a stay on the conflict mineral rule, which some had expected would happen. But the SEC hasn’t said so – at least not yet – so we are all still awaiting that important decision (this WSJ article says that the SEC is preparing to implement the bulk of the rule).
Outside of the context of rule adoption and speeches, it’s pretty rare for Commissioners to issue statements like this to publicly air disputes. However, the Commission increasingly has become partisan over the past decade – and this joint statement is not that big of a surprise given the fight over the conflict mineral rule all along.
What was surprising though was the second news of the day – a dissent on a WKSI waiver! And this time by Democratic Commissioner Kara Stein! I feel bad for Chair Mary Jo White who might have a tougher time garnering consensus going forward. Back when I worked for a Commissioner in the late ’90s, Chair Arthur Levitt rarely would take a matter to a vote unless he knew he had a 5-0 vote in his pocket. That certainly is ancient history…
5 Steps to Becoming a SEC Commissioner
So how does one become a SEC Commissioner anyway? In this 2-minute video, I describe the criteria – in practical terms – of being appointed a SEC Commissioner:
Webcast: “Latest Developments in IPOs & Capital Raising”
Tune in tomorrow for the webcast – “Latest Developments in IPOs & Capital Raising” – to hear Jocelyn Arel of Goodwin Procter; Steve Bochner of Wilson Sonsini; Dave Lynn of TheCorporateCounsel.net and Morrison & Foerster; and David Strong, Partner of Morrison & Foerster explore the latest developments in IPOs and raising capital, including all the various alternatives, such as “Up-C” IPOs, PIPEs and registered direct offerings, “at-the market” offerings, equity line financings and rights offerings – and more…
In this 2-minute video, I run down 23 great ways that Merck enhances the usability of its 2014 proxy statement:
Corp Fin Revises WKSI Waiver Policy Statement Again
Last week, Corp Fin revised its policy statement concerning when it will grant a waiver of ineligible issuer status for WSKIs for the 2nd time over the past few months. The latest revision provides guidance on what constitutes “a showing of good cause”…
Shareholder Proposals: Fracking Proposal Withdrawn at Exxon In Exchange for Disclosure
As noted in this WSJ article, just weeks after Exxon’s agreement to report on climate change and carbon risk, the world’s largest publicly traded oil and gas producer has announced that it will provide increased transparency and disclosure about how it manages the environmental and community impacts of its hydraulic fracturing operations – in response to the withdrawal of a shareholder proposal filed by As You Sow, the New York City Pension Funds, and 12 co-filers.
In a joint policy statement issued last week, the DOJ and FTC officially encouraged companies, including direct competitors, to share cyber threat information with one another. While the statement does not represent a significant policy shift, it is interesting because DOJ and FTC are actively encouraging companies to share this type of information.
Appreciate the many folks – and I truly mean “many” (the power of this blog is that it’s community-based, so keep that feedback coming!) – who forwarded the first Form SD filed with the SEC yesterday. Filed well ahead of the June 2nd deadline for some reason – maybe because the company is based in Taiwan? Siliconware Precision Industries’ Form SD probably should not be used as a template. It will be interesting to see how Corp Fin will go about policing – and enforcing – these Forms during the first year. New disclosure requirements are always challenging – with a wide range of quality. Here are some comments I received from members about this first filing:
– If this is the baseline, we are looking to be in good shape
– While I don’t endorse a lot of detail, this one is almost beyond bare bones
– Good example of “what not to do”
– Interesting that they state that certain products are “conflict free” although they are overall “undeterminable,” which seems to directly conflict with the recent FAQs
– The registrant described its conflict minerals status as “DRC Conflict free,” but no audit was included
– This thing is totally bizarre
Don’t forget the transcript for our popular webcast – “Conflict Minerals: Tackling Your 1st Form SD” – during which Meredith Cross and Dave Lynn imparted lots of important last-minute guidance (which is still valid despite last week’s court case). Meanwhile, some members of Congress wrote this letter to SEC Chair White, urging her to implement the conflict mineral rules as originally scheduled…
7 Ways to Sleep at Shareholder Meetings
This blog says it all about a picture being worth a thousand words. Vanessa Schoenthaler blogs about this fight letter that was filed in the Harvard Illinois Bancorp proxy fight, which features a picture of the company’s chair sleeping during last year’s annual shareholders meeting. Also see this DealBook piece and this article.
In the wake of this “fight letter” being in the news, Dr. Jimmy sits down with me to analyze what sleeping at an annual shareholder meeting really means in this 2-minute video:
Old-Timers Rule! Irv Borochoff Sighting!
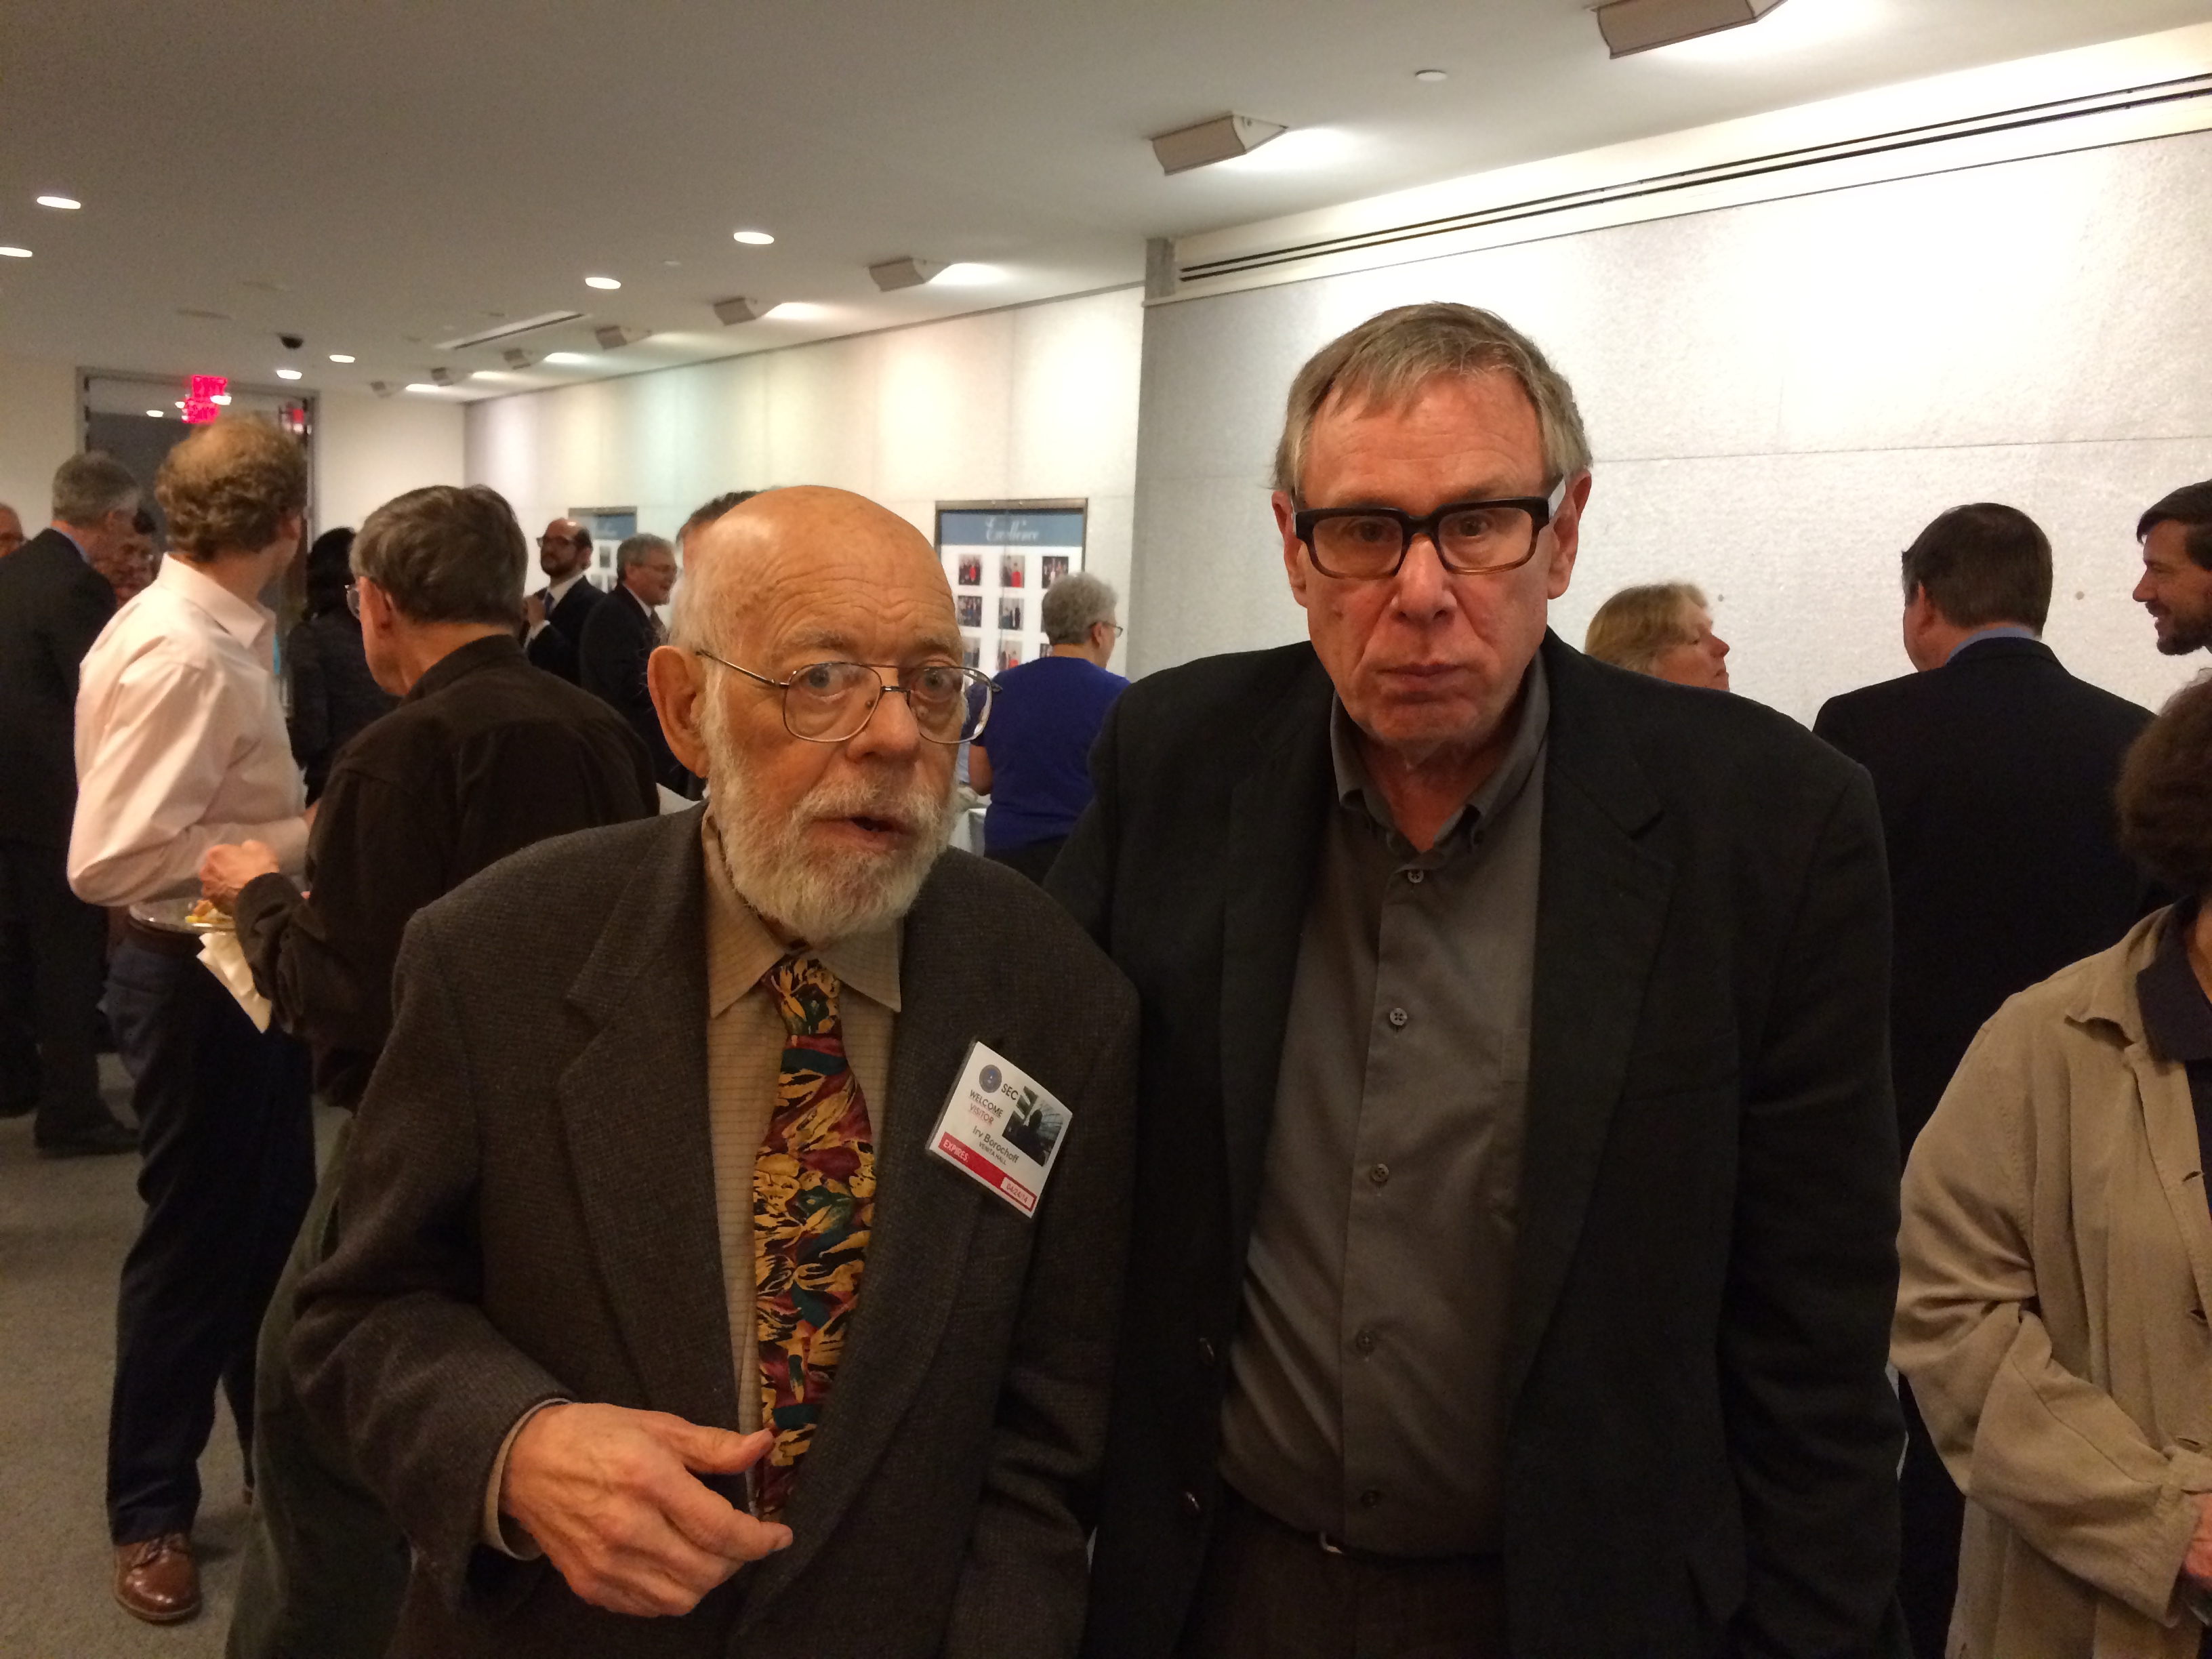
At Mauri Osheroff’s emotional retirement party yesterday, people came back that hadn’t been seen in many years. Former Assistant Director Irv Borochoff – who retired 20 years ago – was among those. Irv was highly respected during his tenure. With him is Bob Belluck, who served under Herb Scholl back in the day (and is still in Corp Fin):
Here’s one note I receive about Irv: “He was a fabulous Assistant Director – so smart and so caring. Some staff members were afraid of Irv but as long as a staff member admitted to not knowing the answer to one of his questions but volunteered to find the answer right away Irv was fine. However, Irv had no patience for staff members who tried to “bluff” him.”
As noted by this WSJ blog by James DeGraw and Lisa Rachlin of Ropes & Gray, companies have been pounded by the latest widespread cybersecurity threat – “Heartbleed,” which is a fundamental flaw of OpenSSL – a popular, widely-used tool for encrypting Internet communications. Doing a quick search on Edgar, I can find no SEC filing that includes the term “Heartbleed.” Perhaps it’s a little early and eventually there might will be some risk factors and other disclosures.
I tend to think that, unless a company had a particular “cyber incident” – to use the SEC’s parlance – related specifically to the Heartbleed OpenSSL flaw, a risk factors disclosure in this area might be more generalized. For example, it might describe risks inherent in relying for cyber risk mitigation on third party or open source software that might contain undetected flaws (i.e. Heartbleed).
Corp Fin’s guidance in this area – CF Disclosure Guidance: Topic 2 (Cybersecurity) – notes that “cyber incidents can result from … unintentional events,” which might include prolonged exposure from security flaws such as Heartbleed, which remained undetected by companies for years. The guidance also notes that cybersecurity risk disclosure must adequately describe the nature of material risks, which might include “risks related to cyber incidents that may remain undetected for an extended period.”
The bottom line is that – unfortunately – securities lawyers will need to learn more about security breaches and cybersecurity threats as they have been a routine part of our daily life with no end in sight. Learn more in our “Security Breaches” Practice Area…
Here’s an Akin Gump’s blog on Congressional hearings on Target and other breaches as well as the SEC’s cybersecurity roundtable (and here’s some memos on the roundtable – and my sober reenactment video).
Mauri Osheroff Retires! Nearly the Last of a Generation
Sad to hear that long-time Associate Director Mauri Osheroff has retired after 40 years of service. Her many accomplishments are documented in this press release. Mauri is one of the last of a generation that led the Division from an era of no computers to a future that no one could imagine. A kind and well-informed soul, she will be missed. I remember first meeting Mauri in 1987 when I was an intern in Corp Fin and she was serving as Deputy Chief Counsel and came in to do a training session. She knew so much even back then!
Will Regulation A+ Make the Grade? Explanation of Comments Received by the SEC