On an ongoing basis, the International Monetary Fund undertakes assessments of the financial regulatory arrangements of countries around the world, which is called the “Financial Sector Assessment Program.” A few weeks ago, the IMF published its FSAP review of the United States, covering banking, insurance and securities. As part of this process, the various regulatory agencies prepare a self-assessment of how they think their agency stacks up against international standards. Here’s the SEC Staff’s self-assessment. It is a remarkable document – 700 pages of the Staff describing its various programs. Principle 16 regarding eliciting disclosure starts on page 244.
Insider Trading: Second Circuit Declines to Review Newman Insider Trading Decision
A few weeks ago, the US Court of Appeals for the Second Circuit denied Preet Bharara’s request that the court reconsider United States v. Newman. By declining to reconsider Newman, the Second Circuit left in place a sharply narrowed definition of insider trading that limits the government’s ability to prosecute insider trading cases (at least in the Second Circuit). The government must now decide whether to appeal to the Supreme Court and/or rely on Congress to adopt legislation providing a statutory definition of illegal insider trading for the first time. As noted in this DealBook column, this is even more notable given that it’s Judge Rakoff that sided with the SEC.
First, the knowledge element could make things very difficult for the SEC and the Justice Department in remote tippee cases. The defendants in Newman, for example, were far removed from the original sources of the information. As the court put it:
“[T]he Government presented absolutely no testimony or any other evidence that Newman and Chiasson knew that they were trading on information obtained from insiders, or that those insiders received any benefit in exchange for such disclosures, or even that Newman and Chiasson consciously avoided learning of these facts.”
One of the things that enterprising inside traders might do as a result is to create some distance between the sources of material, nonpublic information and those who ultimately trade on that information. A person or two in between could mean that the actual traders never know the personal benefit, if any, that accrues to the original tipper. Structuring insider trading chains in this way could become part of the general business model. I mean, this is what people do. The court does seem to allow for liability, as it probably must, if defendants “consciously avoid[] learning of these facts.” But one thing about conscious avoidance – it can be pretty hard to prove! Not impossible, but hard.
Leveraged Loans: Looks Like Securities But Not Regulated?
This Bloomberg article entitled “Loans Look Like Securities Yet Escape Oversight From SEC” is worth reading. Here’s an excerpt:
Leveraged loans look and trade like securities — yet the regulator in charge of overseeing securities doesn’t consider them as such. These loans, usually made to companies with high debt and speculative-grade credit ratings, are made for commercial or consumer — not investment — purposes, according to lawyers and bankers who argue they are not securities. At the same time, the $800 billion leveraged-loan market has become an increasingly popular asset class for pension and mutual funds to invest in. About a third of new loans last year were bought by mutual funds, up from 15 percent in 2012, according to Loan Syndications & Trading Association data.
“If they are syndicating this to investors and indicating there is going to be some liquidity in a secondary market, those are the red flags that make it look very much like a security,” said Thomas Lee Hazen, an expert in securities law at the University of North Carolina School of Law. The U.S. Securities and Exchange Commission’s authority in this market is limited to loans that meet the legal definition of a security, which requires a case-by-case review, according to John Nester, an SEC spokesman.
Here’s an excerpt from this blog by Cooley’s Cydney Posner:
The Corporation Law Section of the Delaware Bar has approved, substantially as proposed, the amendments to the Delaware General Corporation Law proposed by the Delaware Bar’s Corporation Law Council regarding fee-shifting and forum selection provisions in Delaware governing documents. (See this post.) Accordingly, it is anticipated that the proposals would be introduced for consideration by the Delaware General Assembly.
More specifically, the proposed amendments would invalidate, in Delaware charters and bylaws, fee-shifting provisions in connection with internal corporate claims. “Internal corporate claims” are claims, including derivative claims, that are based on a violation of a duty by a current or former director or officer or stockholder in such capacity or as to which the corporation law confers jurisdiction on the Court of Chancery. These claims would include claims arising under the DGCL and claims of breach of fiduciary duty by current or former directors or officers or controlling stockholders of the corporation, or persons who aid and abet those breaches. However, as discussed in this post, federal securities class actions would not be included. The proposed amendments also expressly authorize the adoption of exclusive forum provisions for internal corporate claims, as long as the exclusive forum is in Delaware. Although the proposed amendment does not address the validity of a provision that selects, as an additional forum, a forum other than Delaware, the synopsis indicates that it would invalidate “a forum selection provision selecting the courts in a different State, or an arbitral forum, if it would preclude litigating such claims in the Delaware courts.” Accordingly, the legislation would not allow Delaware corporations to select another state as the exclusive forum.
While not exactly topics roiling the Delaware Bar, a few other matters are addressed in the proposed legislation. For example, with regard to public benefit corporations (see these news briefs and these posts), the proposed amendments would reduce the voting requirement for a corporation to become a public benefit corporation from 90% of the outstanding shares to 2/3 of the outstanding shares (still a rather high hurdle, especially if the company is already public) and provides a market out (applicable to listed companies and companies with over 2,000 record holders) to the provisions allowing appraisal for stockholders that did not vote in favor of the transaction.
Other proposed amendments relate to issuance of stock and options. These proposed amendments clarify that the board may authorize stock to be issued in “at the market” programs without having to separately authorize each individual stock issuance and that the amount of consideration to be received for stock or options may be determined by a formula that references or depends on the operation of extrinsic facts, such as market prices or averages of market prices on one or more dates.
The proposed amendments would also clarify a number of issues in connection with the new Delaware statutes, Sections 204 and 205, that authorize ratification of defective corporate acts by the corporation and the Delaware courts, respectively. Among other things, these amendments would address the situation in which the initial board was not named in the original certificate or properly appointed, allow listed companies to provide certain notices by making public filings, clarify the requirements for certificates of validation, clarify the term “validation effective time” (including allowing the board to designate a future time in some circumstances), clarify that the board may adopt a single set of resolutions ratifying multiple defective corporate acts, and clarify that holders of shares of putative stock would not be considered stockholders entitled to vote or to be counted for purposes of a quorum in any ratification vote and that the only stockholders entitled to vote on ratification are the holders of record of valid stock as of the record date (i.e., ratification of a defective corporate act will not result in putative shares being retroactively validated so that they become entitled to vote).
Meanwhile, the “Delaware Rapid Arbitration Act” has been enacted – see this memo…
Revenue Recognition: FASB Tentatively Decides to Delay New Rules for One Year
Last week, the FASB tentatively decided to defer the effective date of its new standard on revenue recognition for one year. The FASB’s tentative decision will be published for public comment before the Board makes a final decision(see the memos in our “Revenue Recognition” Practice Area).
Webcast: “Proxy Access: The Halftime Show”
We have posted the transcript for our recent webcast: “Proxy Access: The Halftime Show.” Also see the blog I just posted on “The Proxy Blog” running down the stats of how 64 of the companies that received proxy access proposals handled them…
Last week, the SEC brought this enforcement action against Polycom’s former CEO (who was fired in 2013). The company was charged with inadequate proxy disclosure from 2010 to 2013 and improper internal controls. The SEC complaint is filled with striking details (if true) of how the CEO at Polycom created false expense reports so the company would pay for his personal expenses, such as this example:
On July 7, 2012, Miller directed his administrative assistant to buy him two tickets to an August 3, 2012 performance of the Broadway musical Jersey Boys in New York City. On July 24, 2012, Miller emailed his administrative assistant to ask if she had the tickets, and during that exchange he represented, “I am giving the JB tickets as a prize in a NYC PLCM office sales contest…. On PCARD place NYC PLCM Q3 Sales Incentive Contest[.]” At Miller’s direction, his assistant charged $576.20 to her P-Card for two tickets to the show, and submitted the expense for reimbursement with the description that Miller had provided. But Miller’s description of the expense was false, as he again used the tickets to attend the theatre with his girlfriend, and did not give them away to Polycom’s New York sales team or anyone else. Indeed, Miller’s August 3, 2012 night out with his girlfriend in New York cost Polycom more than $1,000. In addition to the tickets, Miller charged more than $275 to his Polycom credit card for post-theatre dinner and later, although he had eaten alone with his girlfriend, emailed his administrative assistant a bogus business description for the meal, including the names of purported attendees from a Polycom customer. Miller also directed his administrative assistant to book a limousine service to take him to the theatre and dinner, for which she charged more than $160 on her P-Card, at his direction, and obtained reimbursement from Polycom.
There are plenty of other examples to pique anyone’s interest. It’s another sad tale of what would seem to be, entitlement and fraud.
The SEC also penalized Polycom $750,000 and issued a cease and desist. The company’s proxy statement said: “No Excessive Perquisites” (emphasis in original) and explaining that “[a] small amount of perquisites are provided to our executives, consistent with the practices of our peer companies.” False and misleading statements, books and records violations, internal accounting controls failure, etc.
And in the complaint, the SEC stated: “Polycom employees discovered that Miller had expensed more than $800 worth of spa gift cards as purported gifts to Polycom employees, but that Miller had actually used the gift cards, at least in part, for himself. In response, Polycom’s CFO raised the issue directly with Miller and suggested a system for further review of Miller’s expense reports to avoid problems in the future. Miller reacted angrily at being second-guessed. On June 26, 2011, the CFO sent Miller an email emphasizing the importance of Miller’s and the company’s disclosure obligations, including a detailed description of the relationship between Miller’s expenses, rules requiring that Polycom disclose all perks he received, and the company’s proxy statements. Notwithstanding the clear instructions provided in Polycom’s annual financial reporting questionnaires, which Miller signed, and the CFO’s personal explanation in June 2011, Miller continued to charge and hide personal expenses from Polycom.”
CII’s New Policy: Automatic Accelerated Vesting of Unearned Equity
Last week, the Council of Institutional Investors approved a policy opposing automatic accelerated vesting of unearned equity in the event of a merger or other change-in-control. The recommended best-practice policy states that boards should have discretion to permit full, partial or no accelerated vesting of equity awards not yet awarded, paid or vested.
Transcript: “The Top Compensation Consultants Speak”
We have posted the transcript for the recent CompensationStandards.com webcast: “The Top Compensation Consultants Speak.”
Recently, the SEC posted these forms that were renewed by the OMB: 10-K, 8-K, S-1 and 10-D. Goodwin Procter’s John Newell has redlined the changes to the updated Form 10-K, which includes one new instruction for asset-backed issuers (see page 5) and numerous typos. John only spent 10 minutes looking – but found over a dozen typos (highlighted on pages 6-12 here)!
In addition, here are redlined versions of the updated Form 8-K and Form S-1, which deletes the definition of “Securities Act” as a cute, and belated, plain English touch. Note the redlines are over-inclusive due to formatting changes between the two files that don’t necessarily reflect actual text changes…
The “SEC Warped on TV” Chronicles: Blacklist
Not that I watch a lot of TV, but I watch enough that I have been periodically moved to blog about how the SEC is mistakenly portrayed on TV shows. But I always forget to do so in the morning. So I’m finally going to run with the ball and blog about an episode of “Blacklist” that I watched from the DVR last night. [Spoiler alert if you watch this show but haven’t watched the latest episode!]
The episode – “Vanessa Cruz” – features a woman who is killing off the supervisors (or otherwise ruining their lives) at a brokerage that had employed her deceased husband. After being framed by the supervisors for insider trading, the husband jumped off a bridge. The FBI heroes ascertain it’s the wife targeting these supervisors years later. They interrogate a man in prison (who unknowingly was framed for a crime by the wife as revenge) who is asked this question:
Liz: Before you made your fortune in the private sector, you worked in the division of corporate finance at the S.E.C.
Apparently, this dude participated in the framing of the husband back when he worked at the SEC; that’s why the wife targeted him. Two things obviously wrong with this scenario:
1. The Division of Enforcement – not Corp Fin – handles insider trading investigations at the SEC. Not to mention that the SEC only has civil authority; the DOJ has the criminal hammer.
2. It’s called the “Division of Corporation Finance” – not “Corporate Finance.” A sure sign of someone who doesn’t intimately know the SEC…
Poll: How Do You Feel About Our Redesigned Home Page?
I’ve given you a month to get accustomed to navigating the redesigned home page on TheCorporateCounsel.net. Now let me know what you think of it:
We recently posted the results from this year’s survey on conflict minerals (here are past survey results):
1. We will file a Form SD this year
– Yes, and it will be our 2nd year filing – 90%
– Yes, but it will be just our 1st year filing – 0%
– No, because we had business changes – 0%
– No, for other reasons than business changes – 0%
– Not applicable – 10%
2. We will use the specific original determination wording for calendar year ’14 even though it’s currently not mandated
– Yes – 24%
– No – 59%
– Not applicable – 17%
3. We have decided to exclude non-metallic forms of 3TG per the letter from the industry groups posted on the SEC’s comment page
– Yes – 18%
– No – 25%
– Not applicable – 57%
4. Our Conflict Minerals Report will reflect significant changes in content, structure or approach from our ’13 CMR
– Yes – 21%
– No – 76%
– Not applicable – 4%
5. We didn’t conduct an Independent Private Sector Audit (IPSA) last year and
– Don’t expect to conduct one for our 2014 report – 100%
– Expect to conduct one for our 2014 report – 0%
6. We expect to conduct an IPSA for your 2014 report and we plan on using a
– CPA firm & the Attestation standard – 0%
– Non-CPA firm & the Performance Audit Standard – 50%
– CPA firm & the Performance Audit Standard – 50%
7. For manufacturers: we are requiring part-level information from our suppliers
– Yes – 38%
– No – 59%
– Not applicable – 4%
8. For suppliers: Our customers are no longer willing to accept company-wide disclosures
– Yes – 16%
– No – 68%
– Not applicable – 16%
– Per this article, SEC Chair White estimates its costs associated with the conflict minerals rule is $2.75 million so far (17k hours or $2.1 million to write the rule; 4k hours or $520k to defend it & $128k to update EDGAR)
– Some auditors are pulling out of the IPSA market per this blog entitled “Psst – Hey Buddy, Wanna Buy a Cheap Conflict Minerals IPSA?”
– Per this blog, if your CY2014 smelter/refiner list is limited to ONLY processing facilities that are CFSI audited or verified, your disclosure may be incomplete (unless CFSI audited/verified facilities actually do make up 100% of the names provided by your suppliers).
Transcript: “Merger Filings with the SEC: Nuts & Bolts”
We have posted the DealLawyers.com transcript for our recent webcast: “Merger Filings with the SEC: Nuts & Bolts.”
As the SEC has been telegraphing through its requests to review corporate agreements, the SEC brought its 1st enforcement action against a company for including improper restrictive language in confidentiality agreements last week. As noted in this press release, KBR agreed to pay a $130k civil penalty and take other remedial actions. It’s clear that the SEC intends to take an aggressive approach to interpreting and enforcing Rule 21F-17. We’re posting oodles of memos in our “Whistleblowers” Practice Area. As this Gibson Dunn memo notes:
A question remains how far the Commission’s enforcement activity will extend beyond confidentiality agreements–like KBR’s–that concern internal company investigations of potential compliance concerns, as distinguished from confidentiality provisions in general employment contracts, for example. Nonetheless, public companies and others will want to examine their existing agreements and practices in light of the SEC’s reading of the Rule, while recognizing that the SEC’s surprisingly broad interpretation of the Rule has not been accepted by any court, and may be at odds with companies’ legitimate interests in protecting trade secrets and other confidential information.
Also see this WSJ op-ed from Gibson Dunn’s Eugene Scalia entitled “Blowing the Whistle on the SEC’s Latest Power Move”…
SEC Tweaks Reg A+ Adopting Release
Hat tip to Richie Leisner of Trenam Kemker for pointing out that the SEC has quietly posted a revised Reg A+ adopting release last week. The revised adopting release now has page numbers all the way through the table of contents – the first version only had page numbers on pages 6 and 7. So if you printed out the release when it first came out, you may want to do so again…
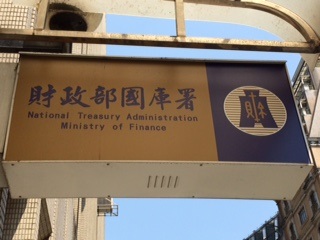
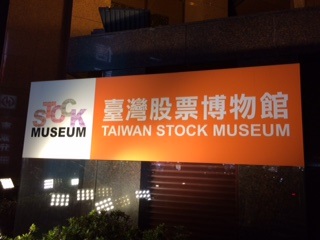
Sights & Sounds from Taiwan
Great trip to Taiwan last week. Loved the country. Didn’t see Taiwan’s SEC – but did run across the Treasury building:
And this museum certainly seems unique:
This video highlights the use of scooters to get around & the popularity of basketball (including among women, who were playing everywhere – nearly as much as the men):
This new KPA Advisory report, based on a recent survey of over 80 major pension funds, identifies a positive correlation between the quality of institutional investors’ internal corporate governance practices and their long-term investment practices. The findings further suggest that better internal governance actually drives long-term investing.
Unfortunately, however, it appears (based on the current as well as prior surveys) that there are significant governance deficits and long-term investing “aspiration vs. reality” gaps that need to be addressed to minimize short-termism and – instead – promote a long-term investment approach.
Principle governance deficits include:
– Board selection and improvement processes continue to be flawed in many cases.
– Board oversight function in many organizations needs to be more clearly defined and executed.
– Competition for senior management and investment talent is often hampered by uncompetitive compensation structures.
Barriers to long-term investing include:
– Regulations that force short-term thinking and acting
– Short-term, peer-sensitive environment that makes it difficult to truly think and act long-term
– Absence of a clear investment model, performance metrics and language that fit a long-term mindset
– Alignment difficulties in outsourcing, and compensation barriers to in-sourcing
This CFA Institute blog – which discusses short-termism factors identified in the report, as well as the short-termism problem more generally – suggests that the time has come for a global set of standards and curricula to govern fund fiduciaries.
See also this 2013 Focusing Capital on the Long Term initiative-driven study revealing perceptions that short-term result pressures have been intensifying – which was the impetus for the current KPA Advisory project.
Building a Board for the Long-Term
This new Spencer Stuart publication is part of a more comprehensive essay collection reflecting the views of CEOs, directors, investors and regulators about what it will take to change current behaviors among companies and investors that compromise long-term growth for short-term gain. The paper provides guidance to boards on how to avoid succumbing to short-termism pressures and act – instead – consistently with a long-term view.
The essay collection is part of the broader Focusing Capital on the Long Term initiative co-founded by CPPIB (Canadian Pension Plan Investment Board) and McKinsey in 2013 to develop practical approaches for longer-term behaviors among both companies and investors.
More on “The Mentor Blog”
We continue to post new items daily on our blog – “The Mentor Blog” – for TheCorporateCounsel.net members. Members can sign up to get that blog pushed out to them via email whenever there is a new entry by simply inputting their email address on the left side of that blog. Here are some of the latest entries:
– Cybersecurity Guidance for Directors
– Directors Logging Many Hours for Board Service
– OECD’s Draft Updated Principles Support Proxy Access
– Under Attack: The SEC’s Use of Administrative Law Judges in Enforcement Actions
– Fine-Tuning Your Section 16 Reporting
This new white paper from Foley provides a practical, easy-to-follow blueprint for directors and officers to tackle cybersecurity. Notably, the paper includes individual “bite-sized” checklists of important considerations covering each of the key elements of a compliance & risk management program. Here are the 10 key elements – each of which is capably addressed with a targeted checklist:
10 Key Elements of a Cybersecurity Risk Management Program
– Incident Management
– User Education and Awareness
– Managing User Privileges
– Home and Mobile Working
– Removable Media Controls
– Malware Protection
– Monitoring
– Secure Configuration
– Network Security
– Cybersecurity Insurance
The paper also includes an information security “policy library” that identifies the most critical policies (e.g., access control, BYOD (bring your own device)) companies should consider as part of their compliance program, and an appendix defining key security concepts.
Effective Use of Internal Audit in Cybersecurity
This new Compliance Week article discusses ways in which companies can tap their internal audit staff to assist with their cybersecurity program, including:
Cybersecurity risk assessment
Identification and inventory of the company’s most important data
Vulnerability testing (to some extent – subject to avoiding independence impairment)
Identification of potential consequences of vulnerabilities
Validation of company’s response plan
Monitoring and periodic testing of program effectiveness
While internal audit functions vary widely, if the company isn’t utilizing internal audit in its cybersecurity assessment and compliance efforts, it’s likely under-utilizing a key resource.
– Substantiation rates for retaliation reports spiked from a consistently historical 10-12% to 27%
– Substantiation rates for repeat reporters are higher than rates for first-time reporters
– Five-year trend of rising report volume continues
– Case closure times continue to climb
– Low rate of anonymous reporters who follow up with their initial report still worryingly low
– Allegations vs. inquiries reveal a fairly steady 80%/20% split
The increasing substantiation rate (i.e., rate of allegations determined to have at least some merit) for retaliation reports – which more than doubled in 2014 compared to 2013 – is particularly noteworthy. As NAVEX Chief Compliance Officer, SVP Carrie Penman noted, while the statistic could be an anomaly, the SEC’s “recent focus on retaliation has caused companies to take a deep dive into these allegations.” Widely publicized, the WSJ recently reported that the SEC sent letters to a number of companies seeking copies of employment agreements and confidentiality training materials since Dodd-Frank’s 2010 effective date that might indicate attempts to stifle employee reporting to the SEC in violation of the law.
Also significant is the higher substantiation rate for repeat reporters. This is important because – at least historically – there has been concern that companies may perceive repeat reporters/complainants as less credible – a practice that SEC Chair White has cautioned against in the past.
See also this more recent WSJ article noting potential challenges to the SEC’s authority to enforce Dodd-Frank’s anti-retaliation provisions.
How to Handle Informal SEC Communications
This recent Compliance Week article provides guidance about how to handle informal SEC communications – including informal requests for information such as the SEC’s recent whistleblower-related inquiry.
According to former SEC enforcement attorney BakerHostetler’s Marc Powers, “Cooperation with the SEC may be in a company’s best interest, but compliance has to be carefully planned and considered. No matter how friendly the voice on the other end of the phone may be, or how cordial a letter is, regulators are not paid to be your friend. ‘If it is an enforcement group, their primary goal is to ferret out wrongdoing from whatever the situation.'”
The article also provides some useful tips from SEC Deputy Chief Accountant Dan Murdock’s remarks at the December 2014 AICPA Conference and, more recently, PLI’s 2015 SEC Speaks conference, about how to most appropriately utilize Staff’s frequent speeches – which often appear to be guidance-like in nature, but are almost always qualified as reflecting the views of the speaker only, not the SEC. For example, he characterized such speeches as generally having a five-year shelf life due to, among other things, evolving staff thinking and business models.
More on “The Mentor Blog”
We continue to post new items daily on our blog – “The Mentor Blog” – for TheCorporateCounsel.net members. Members can sign up to get that blog pushed out to them via email whenever there is a new entry by simply inputting their email address on the left side of that blog. Here are some of the latest entries:
– Are Nominating/Governance Committee Chairs Undervalued?
– CEO Involvement in CEO Succession
– Practical Guidance on Internal Audit Independence
– Enhancing COSO’s ERM Framework
– Bigger Penalties When Whistleblowers Involved
With board composition and renewal under increasing scrutiny, this recent EY reportsummarizing views of institutional investors, investor associations and advisors about board composition and board composition disclosure is instructive.
Among the key findings are that most investors don’t believe companies are doing a good job of explaining why they have the right directors in the boardroom. And the vast majority of investors believe that rigorous board evaluations – not, e.g., director term limits, retirement ages – are the most effective way to stimulate board refreshment.
Based on insights gleaned from the interviews, the report suggests these three ways companies can enhance board composition disclosures:
1.Make disclosures company-specific and tie qualifications to strategy and risk — Be explicit about why the director brings value to the board based on the company’s specific circumstances. Companies should not assume that the connection between a director’s expertise and the company’s strategic and risk oversight needs is obvious. Also, explaining how the board, as a whole, is the right fit can be valuable, particularly given that most investors are evaluating boards holistically.
2. Provide more disclosure around the director recruitment process and how candidates are sourced and vetted — Disclosing more information around the nomination process — how directors were identified (e.g., through a search firm), what the vetting process entailed, etc. — can mitigate concerns about the recruitment process being insular and informal.
3. Discuss efforts to enhance gender, racial and ethnic diversity — Many companies — nearly 60% of S&P 500 companies — say they specifically identify gender and ethnicity as a consideration when identifying director nominees, but that is not always reflected in the gender, racial and ethnic makeup of the board. Disclosing a formal process to support board diversity, including providing clarity around what is considered an appropriate level of diversity, can highlight efforts to recruit diverse directors.
The report also identifies potential disclosure tools, which may include a strategy-based skills matrix, a lead director/chair letter discussing board succession planning/refreshment/composition, and/or shareholder engagement.
Board Skills Matrix Considerations
This recent guidancefrom the Goverance Institute of Australia provides a thoughtful approach to creating or refreshing a board skills matrix – which (regardless of geography) is an effective tool for identifying existing and desired competencies and skills on the board.
Among other things, the guidance addresses:
Potential alternative approaches to identifying existing skills – which may entail involvement by the board chair, corporate secretary, each director individually, the board as a whole and/or the nominating committee
Non-exhaustive list of competencies the board may wish to consider which – aside from the standard fare – may include, e.g., geographic experience, diversity, tenure
Board’s consideration of a deeper dive ratings system to weight each competency (e.g., high, medium, low), as well as perhaps identifying whether the experience was attained in a management or non-management context
Other thoughtful considerations such as whether identified gaps need to be addressed now and – if so, how. Depending on the circumstances, gaps may be satisfactorily addressed via an external subject matter expert, new director(s), management input and/or education/training
This is a good read – even for matrix veterans.
More on “The Mentor Blog”
We continue to post new items daily on our blog – “The Mentor Blog” – for TheCorporateCounsel.net members. Members can sign up to get that blog pushed out to them via email whenever there is a new entry by simply inputting their email address on the left side of that blog. Here are some of the latest entries:
– Survey: Disclosure Committee Insights
– Successful Whistleblower Profile Revealed
– Audit Committee Disclosure: SEC’s Chief Accountant Talks Concept Release
– Waiver of IPO Lock-Ups: Delaware Declines to Dismiss Board, But Dismisses Underwriter Aiding & Abetting
– Making the Case for Fee-Shifting Bylaws