What a freak show the now-aborted WeWork IPO wound up being. For example, this falls into the “news of the weird” category – check out this excerpt from this article about the role the CEO’s spouse played in preparing the company’s Form S-1:
An S-1 is meant to be a bland financial document, but WeWork’s took a different direction. With Adam’s encouragement, Rebekah became unusually involved in the artistic presentation of the document. “The traditional approach to producing an S-1 is bankers and lawyers hashing this out, but the process was continually usurped by Rebekah’s involvement,” one executive said, echoing a sentiment expressed by multiple people who worked on the project. “She treated it like it was the September issue of Vogue.”
WeWork had hired a former director of photography at Vanity Fair, and Rebekah insisted on selecting the photographers chosen to take photos of WeWork offices and members, and approved every photo that appeared in the S-1, of which WeWork included many more than most companies that go public. (She wasn’t the only picky one: Adam Kimmel, the company’s chief creative officer, became unhappy with how the company’s offices looked in its official pictures, so new photographers were sent around the world to reshoot them.)
As the summer wore on, WeWork employees found themselves making so many trips to meet with Rebekah at the Neumanns’ home in Amagansett that “He’s ‘out east’ tomorrow” became a euphemism for describing a colleague spending their day driving to and from the Hamptons. “The thing that’s so damning about all that is that it’s just not the point of the document,” a person who worked on the project said. “That’s the thing about WeWork: You’re spending all this time working on the surface of it instead of the actual truth of the thing.”
CalPERS Votes Against 53% of Pay Plans!
This blog by Jim McRitchie is mindblowing! Here’s a summary:
CalPERS, the largest U.S. pension fund which manages more than $380 billion in assets, has already started implementing its new compensation framework. In an effort to drive more accountability and improved pay for performance alignment, CalPERS reports voting against 53% of compensation plans at portfolio companies during the 2019 proxy season. That is up from 43% last year.
This September-October issue of the Deal Lawyers print newsletter was just posted – & also mailed – and includes articles on:
– Five Observations on Recent Use of Universal Proxies
– Delaware Chancery Upholds Waiver of Appraisal Rights
– Does Your Acquisition Agreement Trigger a Form 8-K?
– Disclosure of Projections: Will Delaware’s Approach Still Rule the Roost?
Right now, you can subscribe to the Deal Lawyers print newsletter with a “Free for Rest of ‘19” no-risk trial. And remember that – as a “thank you” to those that subscribe to both DealLawyers.com & our Deal Lawyers print newsletter – we are making all issues of the Deal Lawyers print newsletter available online. There is a big blue tab called “Back Issues” near the top of DealLawyers.com – 2nd from the end of the row of tabs. This tab leads to all of our issues, including the most recent one.
And a bonus is that even if only one person in your firm is a subscriber to the Deal Lawyers print newsletter, anyone who has access to DealLawyers.com will be able to gain access to the Deal Lawyers print newsletter. For example, if your firm has a firmwide license to DealLawyers.com – and only one person subscribes to the print newsletter – everybody in your firm will be able to access the online issues of the print newsletter. That is real value. Here are FAQs about the Deal Lawyers print newsletter including how to access the issues online.
As it has for the past few election cycles, executive compensation is working itself into the 2020 Presidential campaign. Bernie Sanders announced a proposal this week that would increase the corporate tax rate if a large company’s pay ratio is 50x or more (it would apply to any public or private company with more than $100 million in revenue). Here’s some news articles about it:
If you follow the SEC’s Enforcement actions, you find quite a few that can be entertaining. As Cooley’s Cydney Posner blogs, this one involving Marvell Technology is interesting because the company ran a “revenue management scheme” and the SEC took action not because of the scheme itself, but rather because the company failed to publicly disclose the scheme in its MD&A (or to disclose its likely impact on future performance). The SEC’s order demonstrates that, even if a scheme involving unusual sales practices may not amount to chargeable accounting fraud, failure to disclose may be actionable..
More on “Proxy Season Blog”
We continue to post new items on our blog – “Proxy Season Blog” – for TheCorporateCounsel.net members. Members can sign up to get that blog pushed out to them via email whenever there is a new entry by simply inputting their email address on the left side of that blog. Here are some of the latest entries:
– Firearms Responsibility: Will Shareholders Show Renewed Interest?
– Proxy Voting: Impact of Mutual Fund Board Connections
– Uncontested Director Elections: Impact of Negative ISS Recommendations
– Proxy Plumbing: Recommendations From SEC’s “Investor” Subcommittee
– Shareholder Engagement: A UK Study of Investor Trends
Here’s a blog that I drafted before Corp Fin made its recent announcement about how it will process Rule 14a-8 requests for shareholder proposals going forward – it’s still worth sharing: Last month, I had lunch with a friend who started foaming at the mouth about the need for Corp Fin to remove itself as the referee in the no-action process for shareholder proposals. After his foam had dried, I replied that Corp Fin would like nothing more. The problem historically has been that whenever Corp Fin suggests that it diminish its role, participants on all sides scream bloody murder.
Processing no-action requests under Rule 14a-8 is labor intensive in Corp Fin. Most requests come in during a short window and are time sensitive. The Staffers working on them still have their regular workload to deal with (at least when I served in Corp Fin). Being placed on the “Shareholder Proposal Task Force” feels like punishment. Long hours. Very long. Highly sensitive situations in some cases – the kind that can derail your career. And not exactly intellectually rewarding.
Here’s an excerpt from the SEC’s adopting release in 1998, the last time the SEC significantly changed Rule 14a-8:
Some of the proposals we are not adopting share a common theme: to reduce the Commission’s and its staff’s role in the process and to provide shareholders and companies with a greater opportunity to decide for themselves which proposals are sufficiently important and relevant to the company’s business to justify inclusion in its proxy materials. However, a number of commenters resisted the idea of significantly decreasing the role of the Commission and its staff as informal arbiters through the administration of the no-action letter process. Consistent with these views, commenters were equally unsupportive of fundamental alternatives to the existing rule and process that, in different degrees, would have decreased the Commission’s overall participation.
Processing Shareholder Proposals: Life Can Be Rough
A story to illustrate. When I first joined Corp Fin in ’88 for my first tour of duty at the SEC, I was right out of law school. That was typical back then. And each branch was required to contribute one person to the Shareholder Proposal Task Force. You were “it” if you were the newest person in the branch. So the Task Force was comprised of a dozen people who were right out of law school.
Nothing was electronic back then. We wrote out our analysis & recommendation for each no-action request by hand. There was only one computer for the entirety of Corp Fin. So you would have to wait until “after hours” to be able to access it and print out precedent to support your analysis (the Division had a Lexis account on this prized computer that sat over in the Office of Chief Counsel). To top off this charmed experience, I was chewed out by a crazed supervisor over one of my first recommendations. By the end of his diatribe, he realized he had gone over the top and invited me out to go drink whiskey (I declined).
I wouldn’t blame him except I was right out of law school. My training when I arrived consisted of my boss handing me a rulebook and saying “here, read this over the next week.” So I read S-K – and the ’33 Act &’34 Act rules – straight. Those things are not meant to be read straight. So I learned nothing, Other than that the SEC’s rules & regulations are not written in anything close to plain English. There was literally no training. If you got lucky, your office mate was experienced & willing to teach. Yes, life was tough in the old days…
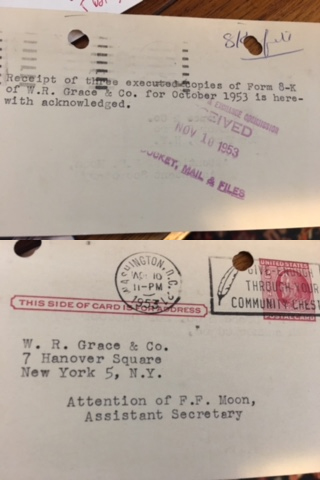
Big hat tip to Sean Dempsey for sending me this awesome receipt – stamped by the SEC – acknowledging the filing of a Form 8-K by his company, W.R. Grace in 1953:
I love hearing stories from old-timers about making filings before Edgar was born. Personally, I remember being on the Corp Fin Staff in the ‘80s & going outside to get a little fresh air on days that happened to be 10-Q or 10-K filing deadline days. The line of FedEx trucks went on for blocks. I barely noticed…
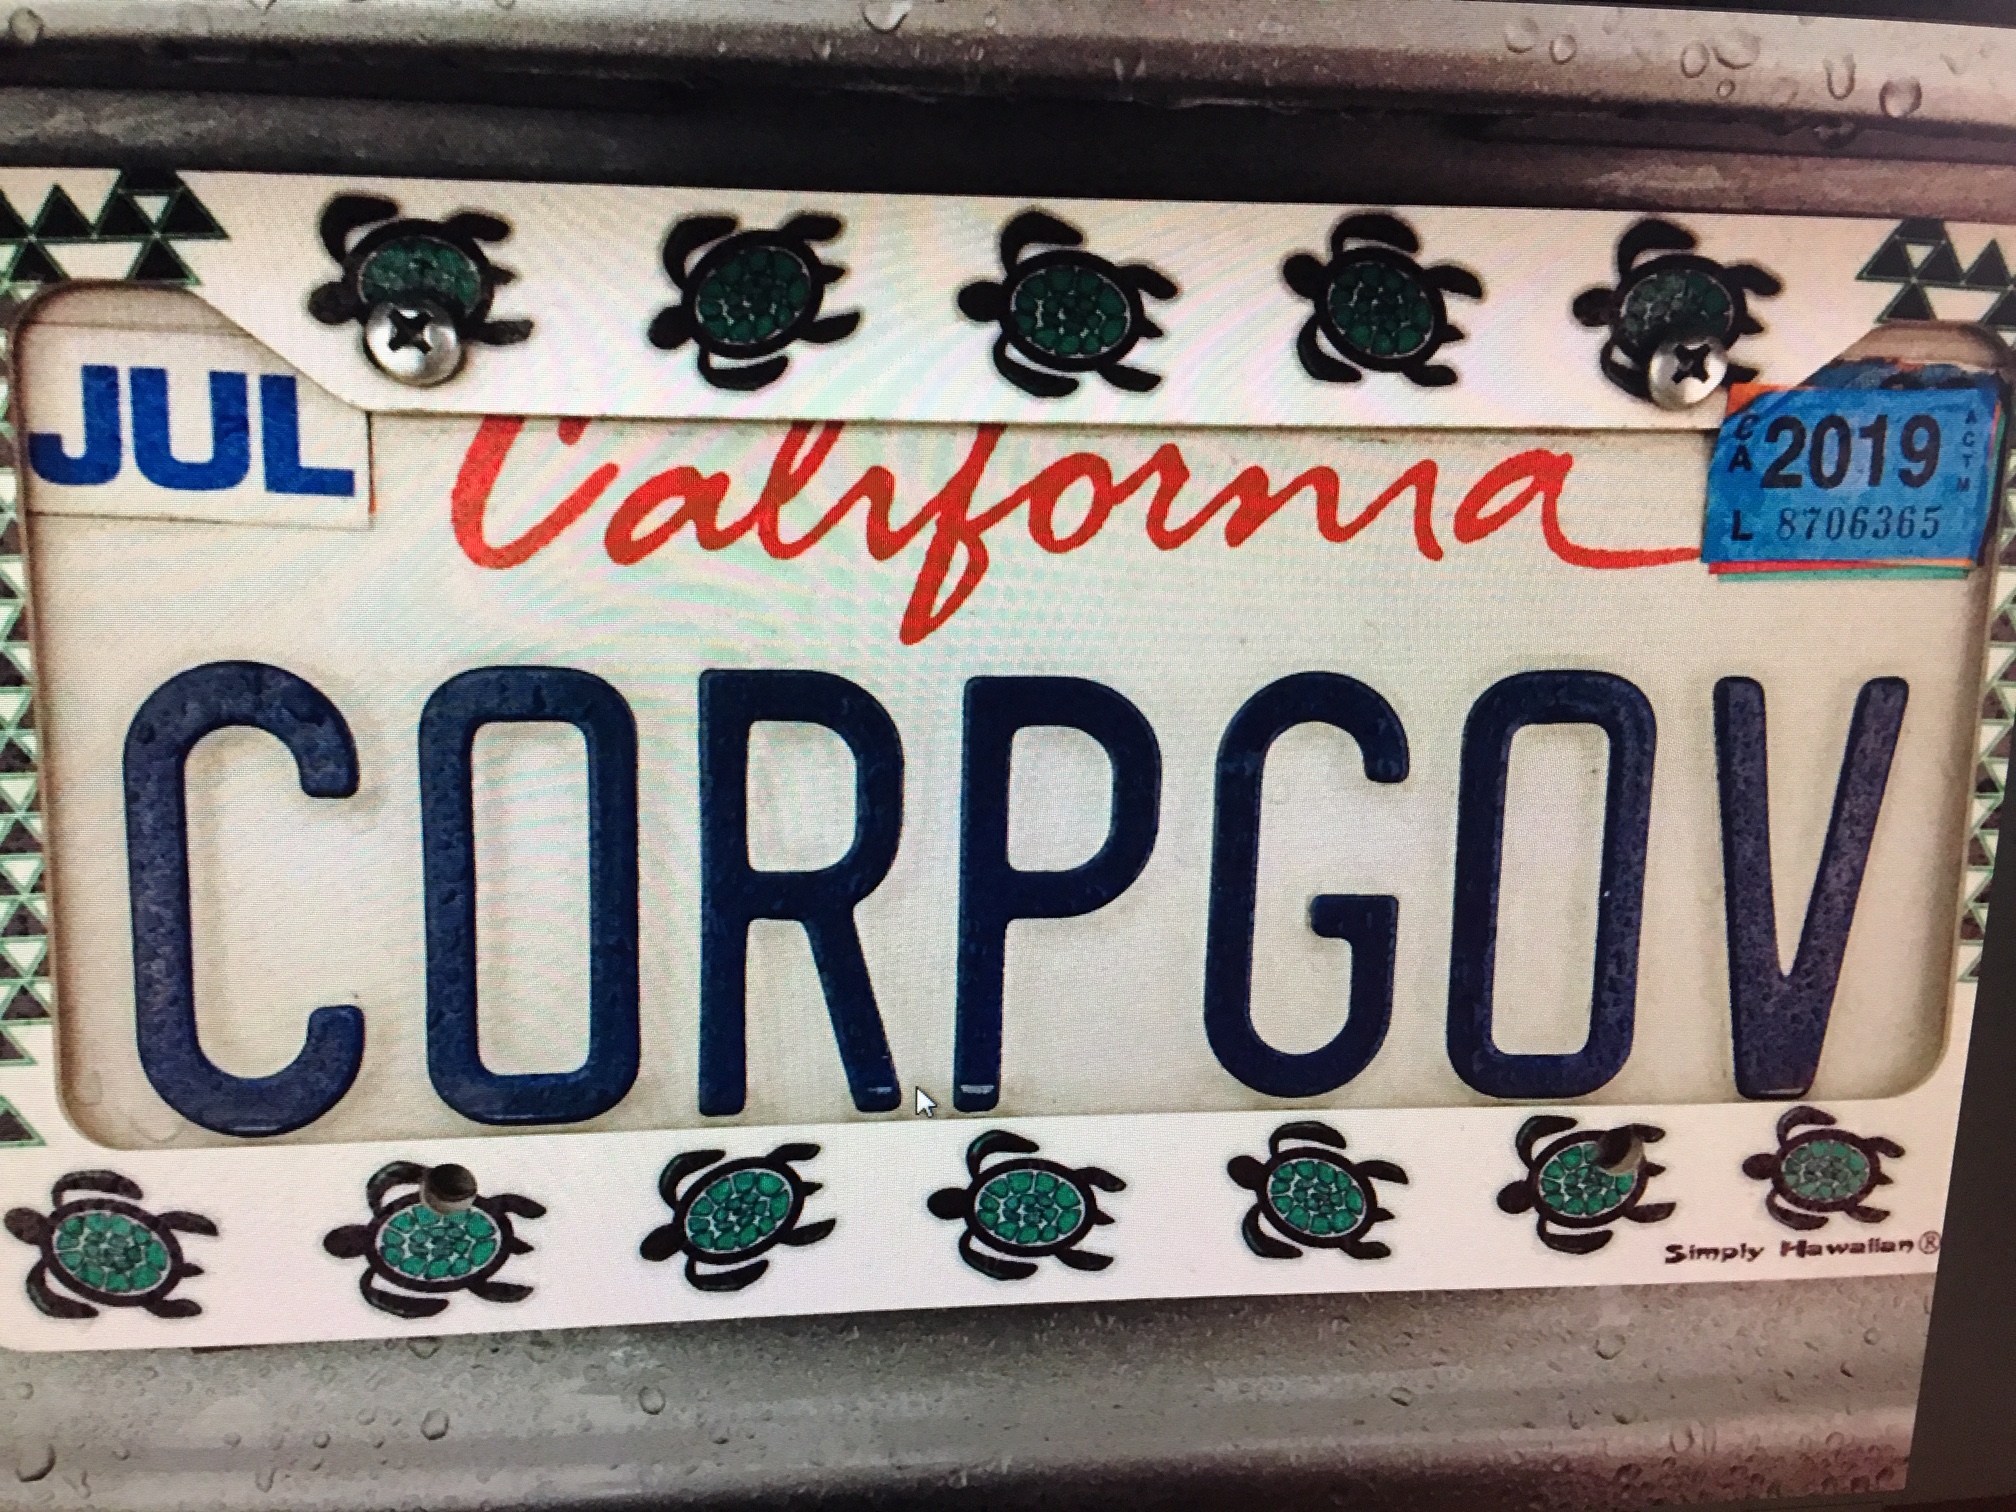
Another Cool License Plate!
Check out this license plate from Jim McRitchie, who has run the “CorpGov.net” website forever (his wife is part-Hawaiian; hence the turtle-themed plate holder):
More on “The Mentor Blog”
We continue to post new items daily on our blog – “The Mentor Blog” – for TheCorporateCounsel.net members. Members can sign up to get that blog pushed out to them via email whenever there is a new entry by simply inputting their email address on the left side of that blog. Here are some of the latest entries:
– Board Evaluations: How They Are Evolving
– Multi-Class Companies: CII Appeals to Delaware
– Crisis Management: Public Relations Considerations
– D&O Insurance: Outlook for 2020
– Gov. Investigations: Key Questions When You Get An Investigative Request
Recently, I blogged about when a SEC Staffer kicks off their public remarks with a disclaimer that their remarks are their own and not those of the Commission. I mused that the origins of this disclaimer seem to have been forgotten. I then heard from a number of members with remembrances and their own research on this topic.
(b) Reference to official position. An employee who is engaged in teaching, speaking or writing as outside employment or as an outside activity shall not use or permit the use of his official title or position to identify him in connection with his teaching, speaking or writing activity or to promote any book, seminar, course, program or similar undertaking, except that:
(2) An employee may use, or permit the use of, his title or position in connection with an article published in a scientific or professional journal, provided that the title or position is accompanied by a reasonably prominent disclaimer satisfactory to the agency stating that the views expressed in the article do not necessarily represent the views of the agency or the United States; and
And former SEC General Counsel Dan Goelzer dug back even further – noting that the disclaimer appears in “Rule 4 (Outside Employment and Activities)” of the SEC’s “Regulation Concerning Conduct of Members and Employees and Former Members and Employees of the Commission.” Rule 4(d)(2)(ii)(A) contains the current version of the disclaimer:
Therefore, such publication or speech shall include at an appropriate place or in a footnote or otherwise, the following disclaimer of responsibility: “The Securities and Exchange Commission disclaims responsibility for any private publication or statement of any SEC employee or Commissioner. This [article, outline, speech, chapter] expresses the author’s views and does not necessarily reflect those of the Commission, the [other] Commissioners, or [other] members of the staff.”
Dan isn’t quite sure when the disclaimer originated, but he does know it was prior to 1980. In 1980, the SEC made various revisions to that conduct regulation – and while a number of changes to Rule 4 are described in that ’80 release, the disclaimer is not one of them. Therefore, we think that the disclaimer was in the pre-1980 version of Rule 4 as well. To bolster the point, Dan sent over two pre-1980 speeches – by Al Sommer (a SEC Commissioner at the time) and Alan Mostoff (then the IM Director) – that include the disclaimer. So it goes way, way, back…
How to Submit Comments on the SEC’s Rulemaking
Among the hundreds of “checklists” posted on our site is this one about how to submit comments on a SEC’s rulemaking. Now the SEC has posted this 90-second video about how easy it is to submit comments on a rule proposal. It has over 350 views within a few months…
Our October Eminders is Posted!
We’ve posted the October issue of our complimentary monthly email newsletter. Sign up today to receive it by simply inputting your email address!
Wow! All that is new is “old” again! When I first joined Corp Fin in 1988, there were a half dozen or so “pods” – each with two branches – that were devoted to specific industries. Each pod was headed by an Assistant Director, which was a difficult job to obtain because a slot only opened when someone retired (back then, it was quite rare for an AD to leave the SEC before retirement). Over time, the Division’s “groups” (as they were eventually renamed from “pods”) grew and the number of them nearly doubled. Now, with this Corp Fin announcement on Friday, we’re going back to the way we were.
Here’s some things to note:
1. Cutting the Number of Groups Nearly in Half – Corp Fin is realigning some of industry groups and reducing them in number from 11 to 7. The groups are now called “Offices” – led by a “Chief” and a “Senior Advisor.”
2. Improving (& Streamlining) the Review Process – Led by an “Office of Assessment & Continuous Improvement,” the teams within Corp Fin that will review filings look to be leaner under this new realigned group structure. There have been fewer comments issued in recent years by the Staff as companies have gotten better observing comment trends and adjusting their disclosures according (not to mention the sheer number of public companies has shrunk a whole lot). Corp Fin will continue to focus on improving the comment process in an effort to be more relevant, timely & consistent.
3. Focus on “Hot” Comment Areas – Led by an “Office of Risk & Strategy,” Corp Fin will focus on emerging issues in their comments – think Libor, cybersecurity and Brexit as recent examples. This Office will review filings for good (or bad) examples of disclosure and then share those internally. It’s something the Staff has already been doing – but it’s now formalizing that function.
4. What Group Is Your Company In? – These seven new groups took effect yesterday – so you can find your new industry group by looking on Edgar for your filing history and noting what “Office” is listed. For example, you’ll see in the 4th line down that Microsoft belongs in the “Office of Technology” group. In many cases, your company’s group will be the same. And if you have a filing that is being actively reviewed right now, the Staffers reviewing your filing aren’t going to change – even if the Office that your company belongs in has changed.
Corp Fin has pulled down its org chart – at least for now. We just deleted our own more comprehensive Corp Fin org chart. I’ve maintained it for 17 years but it’s become too hard to keep up. That was a harder task than you would think – very few people even within Corp Fin know the identities of all the middle managers, etc. A constant game of “Where’s Waldo”…
SEC Proposes to Modernize the OTC Market
Last Thursday, the SEC proposed to modernize the over-the-counter market (OTC) by proposing changes to Rule 15c2-11, which sets out certain requirements with which a broker-dealer must comply before it can publish quotations for securities in the OTC market. Here’s the 228-page proposing release.
Moody’s “Governance” Framework for Credit Ratings
Recently, I blogged how Moody’s was getting into the governance ratings business – but as I noted in that blog, Moody’s has scored governance for quite some time for their credit ratings business. Recently, Moody’s issued a framework to help understand key aspects of governance that are incorporated into all Moody’s credit ratings and analysis, including two taxonomies: a private taxonomy, which applies to non-financial corporates, financial institutions, infrastructure, structured finance and certain competitive government-owned enterprises; and a public taxonomy, which applies to sovereign, sub-sovereign and municipal issuers…
Yesterday, the SEC announced that it had adopted final rules permitting all companies to gauge market interest in a possible initial public offering or other registered securities offering to “test the waters” by reaching out to certain institutional investors before filing a registration statement. Previously, only EGCs had been able to engage in this activity under applicable provisions of the JOBS Act. Here’s an excerpt from the fact sheet included in the press release summarizing the rule:
Securities Act Rule 163B will permit any issuer, or any person authorized to act on its behalf, to engage in oral or written communications with potential investors that are, or are reasonably believed to be, QIBs or IAIs, either prior to or following the filing of a registration statement, to determine whether such investors might have an interest in a contemplated registered securities offering. The rule is non-exclusive and an issuer may rely on other Securities Act communications rules or exemptions when determining how, when, and what to communicate about a contemplated securities offering.
Under the rule:
– there are no filing or legending requirements;
– the communications are deemed “offers”; and
– issuers subject to Regulation FD will need to consider whether any information in a test-the-waters communication would trigger disclosure obligations under Regulation FD or whether an exemption under Regulation FD would apply.
In a public statement accompanying the announcement of the new rule, SEC Chair Jay Clayton said that it will allow issuers to “better identify information that is important to investors and enhance the ability to conduct a successful registered offering, ultimately providing both Main Street and institutional investors with more opportunities to invest in public companies that, in turn, provide ongoing disclosures to their investors.” The new rule will become effective 60 days after publication in the federal register.
Auditor Independence: Flurry of SEC & PCAOB Enforcement
Earlier this week, the Division of Enforcement announced a settled enforcement proceeding with PwC arising out of alleged violations of the SEC’s independence rules. PwC’s Mexican affiliate was also sanctioned for independence violations by the PCAOB in August. The SEC’s action against PwC comes on the heels of another settled proceeding late last month involving RSM US LLP. Earlier this month, the PCAOB sanctioned another two accounting firms for independence violations.
So, what’s with this recent spate of enforcement proceedings? It’s hard to say for sure, but this may have been coming for quite some time. Broc blogged last year that Lynn Turner reported that there was “trouble brewing” at the PCAOB & SEC over independence issues. The PCAOB apparently discovered a number of independence issues in its 2016 inspection reports, and noted that many of these were not reported to the audit committee as required under PCAOB rules.
Earlier this year, the PCAOB came out with additional guidance on what the rules require auditors to communicate to audit committees when they identify independence issues, and the failure to comply with independence disclosure requirements is at the heart of both the PCAOB & SEC enforcement proceedings involving PwC.
PCAOB: Board Laying Low in Wake of KPMG Scandal?
Speaking of the PCAOB, according to this article by MarketWatch.com’s Francine McKenna, the PCAOB continues to be in transition in the wake of the KPMG scandal – and its board has apparently decided to keep a very low profile, even if that appears to violate the PCAOB’s bylaws:
The PCAOB board is staying out of the public eye in 2019, in violation of bylaws established by the law that created the PCAOB, the Sarbanes-Oxley Act of 2002. The law requires the PCAOB to hold at least one public meeting of its governing board each calendar quarter. However, the PCAOB board has held no public meetings of its governing board since December 20, 2018.
MarketWatch asked the PCAOB to comment on its apparent lack of compliance with its bylaws regarding open board meetings. A PCAOB spokeswoman told MarketWatch, “Consistent with long-standing practice, the Board holds open meetings to take action on business such as standard-setting or voting on its budget and strategic plan. We expect to hold two open meetings in the coming months to address our 2020 budget and a proposed concept release related to our quality control standards.”
Even by current D.C. standards, the PCAOB’s response leaves much to be desired. It’s not a denial, and it isn’t even a “non-denial denial.” By the way, it isn’t just the board – the article says that the PCAOB’s two outside advisory groups haven’t met in 2019 either.
I have a friend who keeps trying to persuade me to buy a Tesla. He owns one, and I guess there’s some kind of bounty the company pays to Tesla owners who convince other people to pony up for their own E-Z-Go on steroids. I’ve told him he’s barking up the wrong tree. I’ve always driven a beater. My current ride is a 2012 Chevy Equinox with 140,000 miles on it. It goes through 2 quarts of oil a month and I’m still determined to keep it for at least another couple of years.
But I also confess that even if I was in the market for a new car, I just can’t see buying one from Elon Musk. The guy’s antics really rub me the wrong way. So it pains me to have to blog about him again – but I do. This time, Elon and his board have gotten themselves sideways with Tesla shareholders in the Delaware Chancery Court, and the issue isn’t his tweets, it’s his comp.
Last year, the Tesla board – and shareholders – signed-off on a pay deal that would provide Musk with a potentially gargantuan payout if its stock hit some very aggressive market cap & operational goals. How gargantuan? Try more than $50 billion. A shareholder subsequently filed a lawsuit against Musk and the Tesla board alleging that the comp award was a breach of fiduciary duty.
By way of background, the Chancery Court decided last year that Musk was a “controlling shareholder” of Tesla in an unrelated case, despite the fact that he owned only around 20% of the stock. So, for purposes of the motion to dismiss filed in this case, the parties treated him as if he was a controller. That complicates things considerably, because the default standard for reviewing for transactions between a company and its controlling shareholder – even comp decisions – is the demanding “entire fairness” standard and not the deferential business judgment rule.
Delaware has laid out a path to the business judgment rule for these transactions, but in his 40-page opinion denying the defendants’ motion to dismiss, Vice Chancellor Slights found that despite the approval of the comp award by Tesla’s shareholders, the process wasn’t good enough to allow this award to make the cut:
Had the Board ensured from the outset of “substantive economic negotiations” that both of Tesla’s qualified decision makers—an independent, fully functioning Compensation Committee and the minority stockholders—were able to engage in an informed review of the Award, followed by meaningful (i.e., otherwise uncoerced) approval, the Court’s reflexive suspicion of Musk’s coercive influence over the outcome would be abated. Business judgment deference at the pleadings stage would then be justified. Plaintiff has well pled, however, that the Board level review was not divorced from Musk’s influence. Entire fairness, therefore, must abide.
The Vice Chancellor held that the defendants were unable to establish that the award was entirely fair at the pleading stage, so he declined to dismiss the plaintiff’s breach of fiduciary duty & unjust enrichment claims. That probably means I’ll have to blog about Musk again at some point in the not-too-distant future. Lucky me.
SEC Settles Nissan Fraud Charges: Don’t Have the CEO Set Their Own Pay!
It’s been a big week for CEO compensation stories. Here’s something Liz blogged earlier this week on CompensationStandards.com: Wow. Broc & I have blogged a couple of times over the past year about the SEC’s Nissan investigation, which (among other reasons) is of interest because Nissan is a Japanese company, and also because of the bold efforts people took to conceal former CEO Carlos Ghosn’s pay.
Yesterday, the SEC announced that it settled Section 10(b)/Rule 10b-5 fraud charges with Nissan, Ghosn, and a former director/HR exec for omitting $140 worth of Ghosn’s compensation from Japanese securities filings – which were published in the US because the company’s securities trade as ADRs on the OTC – and which required information about executive pay. Allegedly, Ghosn went to all this effort to restructure & hide his pay because he was worried that people would criticize the amounts (pro tip: at least in the US, that’s a hint that you’re probably required to disclose the info).
Nissan is ponying up $15 million – while the individuals are getting off with civil fines of $1 million and $100k. Seems like a pretty good deal for those two, based on the allegations in the SEC’s complaint against them – e.g., Ghosn first brainstormed ways to conceal part of his pay by paying it through Nissan-related entities…when that didn’t work, he started entering into secret contracts with employees and executing backdated letters for LTIP awards, and decided that “postponing” pay (along with creative accounting) would get him around the disclosure obligations.
Initially, one problem here for the company might have been faulty internal controls. But according to the SEC’s complaint against the company, the fatal blow was that because Nissan had specifically delegated to Ghosn the authority to set individual pay arrangements – including his own! – he was acting within the scope of his employment when he intentionally misled investors, and the company was liable under the principles of respondeat superior. We can complain all we want about the burdensome listing rules here, but maybe they’re saving some companies from themselves…
Audit Reports: What Does Auditor Tenure Disclosure Look Like?
This Audit Analytics blog discusses the disclosures that accounting firms are including in their audit reports in response to the relatively new requirement to disclosure their tenure with a particular company. The blog says that although the PCAOB has provided guidance on determining & reporting tenure, “auditors have discretion regarding exactly what and how the information is disclosed, resulting in substantial variation in disclosures.”
Having reviewed the blog, I can assure you that auditors have used their discretion to ensure that all versions of tenure disclosure are extremely boring.
This Stinson blog highlights rule changes that could prompt a few tweaks to D&O questionnaires. Specifically, the blog notes that:
– Companies can now rely on Section 16 filings & written representations to determine whether an insider has delinquencies. As a result, companies may ask whether all required Section 16 reports have been filed on EDGAR instead of asking whether all of those reports have been provided to it.
– If Nasdaq’s proposed changes to the definition of the term “family member” are approved, Nasdaq-listed companies may want tweak the definition contained in their D&O questionnaires to reflect the changes.
The blog also urges companies to be cautious about eliminating references to Section 162(m) in D&O questionnaires for compensation committee members unless it’s clear that the committee isn’t required to administer any compensation arrangements under the transition rule.
Stinson’s blog is a reminder that although it may seem like proxy season just ended, it’s actually right around the corner. And to help you get ready, we’ve already scheduled our “Pat McGurn’s Forecast for 2020 Proxy Season” webcast for January 16th.
Today’s Open Commission Meeting: Cancelled
The SEC has cancelled the open meeting that it had previously scheduled for today to consider, among other things, adopting its “test the waters” for all proposal. No word on rescheduling yet.
I don’t know if this had anything to do with the decision to cancel the meeting, but all 5 Commissioners were grilled for several hours yesterday by the House Financial Services Committee. Committee Chair Maxine Waters (D – Cal.) opened the hearing with a statement that accused the SEC of “not fulfilling its mission as Wall Street’s cop.” No doubt a good time was had by all.
ESG: Investors Want Companies to Align with Paris Climate Goals
According to this Ceres press release, a group of 200 socially conscious institutional investors with more than $6.5 trillion in AUM sent a letter to 47 large public companies asking them to align their climate change lobbying activities with the Paris Agreement’s goal of limiting global temperature increase to less than 2° C and pursue efforts to hold it at 1.5° C.
The group’s letter doesn’t just address the lobbying activities of the individual companies – it also calls upon them to review those of any trade associations to which they belong and engage with the organization if its activities are inconsistent with the Paris Agreement’s goals. If companies are unable to persuade the association to modify its position, then the signatories ask that they “consider taking the steps necessary to disassociate your company from these policies.”
This SEC Institute blog flags a recent CFA Institute member survey addressing quarterly reporting & ESG disclosure. This excerpt says that quarterly reports are more important to investors than earnings releases, and that those reports & releases should be provided simultaneously:
The majority of survey respondents state that investors heavily rely on earnings releases because they are generally issued before quarterly financial reports. Respondents, however, indicate that quarterly reports remain more important to investors than earnings releases.
These quarterly reports provide a structured information set that follows accounting standards and regulatory guidelines and include incremental financial statement disclosures and management discussion and analysis. In addition, quarterly reports offer greater investor protections as they are certified by the officers of the company, subject companies to greater legal liability, and are reviewed by company auditors.
As for timing, the majority of respondents believe quarterly reports and earnings releases should be provided simultaneously because this would reduce the significant amount of time spent reconciling the contents of earnings releases with those of quarterly reports as well as ensure that investors can ask better questions during earnings calls by having access to the more detailed information contained in the quarterly report. Roundtable participants agree with these positions.
I understand why investors might like earnings releases & SEC reports to hit simultaneously, but I think many lawyers would say that idea is a non-starter. The problem is that earnings calls can go in all sorts of directions, and a lot of companies want to have the opportunity to take a last look at their draft filings make sure that all topics addressed in the call are appropriately addressed in what gets filed with the SEC. If they’re not, companies risk hearing about it in a Staff comment.
By the way, the survey also says that investors have no taste whatsoever for alternatives to 10-Q reporting or less frequent reports, and want companies to continue to provide quarterly earnings guidance.
When it comes to ESG reporting, the survey says that investors are for it, but because ESG means different things to different people, securities regulators need to provide uniform standards in order for that disclosure to be meaningful.
SEC Enforcement: Who Needs a CFO When You Have a POA?
Every now and again you stumble across an SEC enforcement proceeding that can only be described as “goofy.” I think the recently announced action against former Viking Energy CEO Tom Simeo easily qualifies for that description. According to the SEC’s press release announcing the litigation, the CEO “created the false impression to the public that Viking had an experienced financial professional involved in its operations and financial reporting as its CFO, when in reality, the Company had no CFO.”
At one point, the company apparently did appoint Guangfang “Cecile” Yang as its CFO, but the SEC alleges that there’s no evidence that she actually functioned as CFO “from at least November 2014 through Yang’s purported resignation in July 2016.” While the company didn’t actually have a CFO, according to the SEC’s complaint, the CEO did have something else:
One day after her appointment as Viking’s CFO, Yang also executed a power of attorney in favor of Simeo, authorizing Simeo to affix Yang’s signature to any and all documents – including filings with the SEC – that Yang was required to review and sign as Viking’s CFO and board member. The Company never disclosed in its filings that Yang had executed a power of attorney in favor of Simeo.
Simeo allegedly put that POA to good use, liberally affixing the purported CFO’s signature to various SEC filings & certifications. For some reason, the SEC appears to have found that troubling. . . .
Transcript: “Secrets of the Corporate Secretary Department”
We’ve posted the transcript for our recent webcast: “Secrets of the Corporate Secretary Department.”