In light of the SEC’s recent trend of tacking on “disclosure controls” violations to charges about non-financial disclosures, I was somewhat heartened to see that the recent “director independence” enforcement action reflected a settlement with the former director, but no action against the company.
It appears the company took standard steps to collect info about director relationships that might affect the “independence” determination:
– Providing a questionnaire with a non-exclusive list of relationships that could affect independence and asking both broad & specific questions to gather information,
– Instructing D&Os to “exercise great care” in providing answers (worth a shot!), and
– Giving the director the opportunity to review and comment on the proxy statement before it was published.
Alas! Although it’s still nice the company wasn’t charged with wrongdoing here, it’s a stretch to rely on this settlement for comfort that these steps will always be adequate. That’s because, in this particular case, it appears the SEC just brought charges relating to proxy disclosures under Exchange Act Section 14(a) and Rule 14a-9 (even though this disclosure had been incorporated into the company’s Form 10-K). If there were no Section 13(a) charges, a disclosure controls charge would be off the table.
The gist of the rule, as amended, is that if you use a reverse stock split to regain compliance with the minimum bid price requirement, and that causes you to fall below the minimum number of publicly held shares and holders that Nasdaq standards require, you don’t get extra time to cure the new violation. The SEC notice gives more detail – here’s an excerpt (also see this Cooley blog):
Under the proposed rule, such company will not be considered to have regained compliance with the Bid Price Requirement if the company takes an action to achieve compliance and that action results in the company’s security falling below the numeric threshold for another Exchange listing requirement without regard to any compliance periods otherwise available for that other listing requirement. In such event, the company will continue to be considered non-compliant until both: (i) the other deficiency is cured and (ii) thereafter the company meets the bid price standard for a minimum of ten consecutive business days, unless Nasdaq staff exercises its discretion to extend this ten-day period as discussed in Rule 5810(c)(3)(H).
If the company does not demonstrate compliance with (i) and (ii) during the compliance period(s) applicable to the initial bid price deficiency, Nasdaq will issue a Staff Delisting Determination Letter.
This rule is separate from the one I blogged about earlier this week on “accelerated delistings” for penny stocks – although both involve Rule 5810. In fact, this blog has been corrected a couple hours after publication to reflect the distinction. Nasdaq probably had good reasons for making these two separate proposals, but those reasons aren’t clear to me, and I apologize for adding to any confusion in the original blog post!
Spencer Stuart recently published its 2024 Board Index – which always includes valuable data points about board composition and governance practices in the S&P 500. The Index also spotlights trends over the 1-, 5-, and 10-year periods.
One thing that jumped out, which Meredith also discussed in a recent podcast with ESGAUGE’s Paul Hodgson, is the small but noticeable shift away from mandatory director retirement policies. According to Spencer Stuart’s data, 67% of S&P 500 boards still have a retirement policy – but that’s a decrease from 69% last year and 73% in 2014. Moreover, at companies that do have policies in place, the mandatory retirement age has been creeping up (from approximately 72 to approximately 75, with the average being 74). This A&O Shearman memo from late last year articulates why some companies are reconsidering mandatory retirement policies:
Given the challenges described above and the focus on individual directors, it seems certain that boards will feel a sense that the pace of the need for refreshment is accelerating. Traditional models for ensuring reasonable turnover on the board, such as mandatory retirement age and term limits are blunt tools that may not result in the optimum outcomes in terms of board configuration and deliberation, especially at crucial moments in a company’s evolution. Also, these approaches may lead to a loss of experience, leadership or critical skills at an inopportune time.
Boards need to consider whether these methods operate as crutches to avoid difficult interactions about continued service or hobble their plans for refreshment. A flexible approach, where length of service and other factors are considered in the renomination process, may prove more effective, especially if coupled with a board culture that is more accepting of director departures when tenure, skills or other factors call for it, fostered by strong leadership and constant communication about the board’s needs.
Spencer Stuart’s 2024 Board Index shows that the move away from mandatory retirement policies isn’t happening in a vacuum. 28% of boards work with a third party to facilitate the evaluation process (up from 25% last year), and 47% conduct individual director evaluations as part of their process. Additionally, in just 4 years, the percentage of boards that include a director skills matrix in their proxies has almost doubled (from 38% in 2020 to 73% in 2024).
The result of all this work on refreshment? In 2024, boards across the S&P 500 added a total of 406 new independent directors, which is up from last year but down from the 432 directors added in 2019. Average tenure is unchanged from last year – but it’s dropped by 3% over the past 5 years and 7% over the past 10 years. I’m cautious about drawing too many conclusions from high-level stats, when boardroom dynamics are so company specific. But it appears that *maybe* third-party evaluations, investor voting policies, and a shareholder activism environment where “nobody is safe” may be spurring the types of hard conversations that actually affect the refreshment rate.
“You get out of it what you put into it,” is how my high school track coach always responded when we begged for an “easy” practice. As much as I disliked that response back then, over the years I’ve found that it’s a workable mantra for just about any scenario: including board evaluations.
We all know that there’s a wide divergence across the 99% of companies who conduct some form of evaluation. The Spencer Stuart 2024 Board Index offers a couple of pointers that can help turn board assessments into a meaningful tool for continuous improvement. Here’s an excerpt:
– Run frequent & robust board assessments: Boards should conduct meaningful evaluations via an independent third party every two or three years. In addition, the annual evaluation should include getting feedback from the management team to ensure a 360-degree review process for assessing the board’s contributions, effectiveness and areas for improvement.
– Implement individual director evaluations: Peer evaluations, carried out by an independent third party, should be conducted every two or three years.
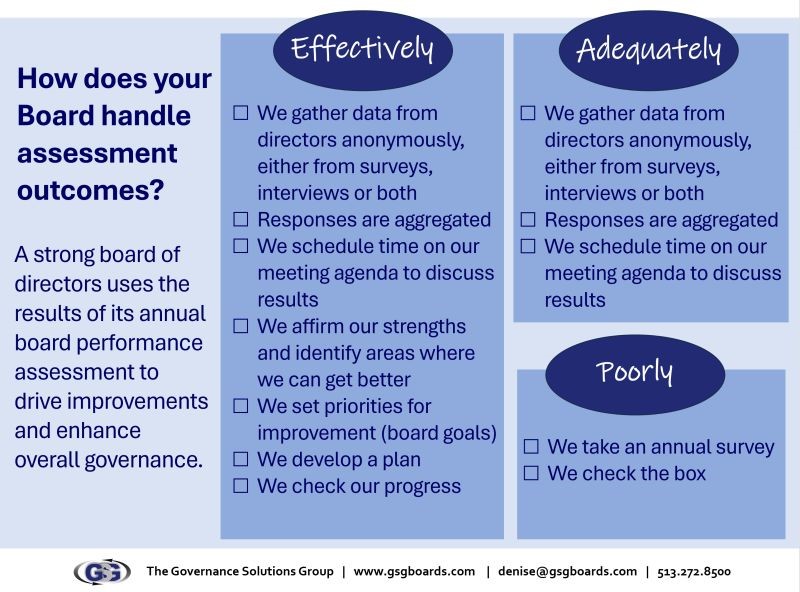
I also love this infographic from Denise Kuprionis at The Governance Solutions Group, which shows that a few basic steps can help boards get more out of the evaluation process:
Yesterday, the NACD announced a new “Blue Ribbon Commission” report to assist directors with overseeing the strategic opportunities & risks of rapidly evolving technologies. If you’re advising boards, be on alert that this may prompt questions and/or projects. The Executive Summary articulates the factors driving “technology governance” – and provides 10 recommendations for boards:
Strengthen Oversight
1. Upgrade board structures for technology governance.
2. Clearly define the board’s role in data oversight.
3. Define decision-making authorities for technology at board and management levels.
4. Ensure trustworthy technology use by aligning it with the organization’s purpose and values.
Deepen Insight
5. Establish and maintain necessary technology proficiency among the board.
6. Evaluate director and board technology proficiency.
7. Ensure appropriate and clear metrics for technology oversight.
Develop Foresight
8. Recognize technology as a core element of long-term strategy.
9. Design board calendars and agendas to ensure appropriate focus on forward-looking discussions.
10. Enable exploratory board and management technology discussions.
It’s worth noting that at many companies, the strategic importance of technology is one of the factors influencing board refreshment. The Spencer Stuart 2024 Board Index reports that technology/telecommunications was the most common industry background of new directors who joined S&P 500 boards this past year. That said, while it’s helpful to have a “tech director,” they typically aren’t “one-trick ponies” – and the full board (or a committee) still has oversight responsibility. NACD’s toolkit (for members) includes resources on evaluating director technology proficiency and assessing technology governance.
It’s hard to believe we are just one week away from our “Proxy Disclosure & 21st Annual Executive Compensation Conferences” – bundled together as one great event that you can attend with us in person in San Francisco or virtually!
On October 14th, we’ll take a deep dive into the upcoming proxy season with the “2024 Proxy Disclosure Conference” – with panels on shareholder activism, governance & disclosure of AI, cyber-related disclosure trends, shareholder proposal trends, climate disclosure updates, and more. Plus, you don’t want to miss our first-ever “All-Star Feud,” during which our intrepid “SEC All-Stars” will face off gameshow-style over burning questions on proxy disclosure and executive compensation.
On October 15th, we turn our attention to critical executive compensation matters at the “21st Annual Executive Compensation Conference” – including key updates on proxy advisors, clawback practices, compensation trends, and perks.
In addition to live and on-demand access to these fast-paced sessions, Conference attendees get exclusive access to our Course Materials – which include unique & practical bullet points and examples from our experienced speakers on each topic we’ll be covering. Our speakers go the extra mile to provide usable takeaways. The Course Materials are an invaluable resource to refer back to as proxy season approaches!
For those seeking CLE credit, here’s a list of states in which credit is available – and CLE FAQs about live and on-demand credit.
Act Now: The Conferences begin next Monday, October 14th. With 17 sessions over 2 days, you’ll walk away with action items to help support director elections and say-on-pay, leverage your executive compensation, and avoid costly mistakes. You can still register. Sign up online or by calling 1-800-737-1271.
Lastly, if you have registered, remember that your unique access link and attendance instructions will be emailed to you from no-reply@events.ringcentral.com. Here’s more detail on what to watch for.
Late last week, the SEC posted notice that it was extending the time period for action on Nasdaq’s proposal to accelerate the delisting process for non-compliance with minimum bid price requirements. I blogged about the proposed amendment when it was published in August – and Meredith shared follow-up commentary that AI and biotech startups are most at risk of delisting if the rule is approved.
The Commission has now designated November 21st as the date by which it will either approve or disapprove, or institute proceedings to determine whether to disapprove, the proposed rule change.
I’m delighted to return, with Vontier’s Courtney Kamlet, for the 6th season of our “Women Governance Trailblazers” podcast. In our latest 20-minute episode, we interviewed Karen Boykin-Towns, who is an independent director at iFit, Vice Chair of the NAACP National Board of Directors, President/CEO of Encore Strategies, and a Senior Advisor of FGS Global. Karen is also a former Pfizer executive (her leadership roles include its first-ever Chief Diversity Officer in 2008). We discussed:
1. Karen’s career path, current endeavors and what she’s been most proud of over the course of her career.
2. Karen’s thoughts on the current state of corporate diversity, equity and inclusion programs and commitments.
3. How companies can balance the call to numerically measure progress in DEI initiatives with the arguments that inclusion can’t be measured and that quotas create legal risk.
4. Karen’s experience on the iFit board, including the decision to withdraw the company’s IPO.
5. Advice to boards and management for adapting to rapidly shifting information, and for monitoring their corporate reputation and emerging issues before they become a crisis.
6. What Karen thinks women in the corporate governance field can add to the current conversation on the societal role of companies.
To listen to any of our prior episodes of Women Governance Trailblazers, visit the podcast page on TheCorporateCounsel.net or use your favorite podcast app. If there are “women governance trailblazers” whose career paths and perspectives you’d like to hear more about, Courtney and I always appreciate recommendations! Shoot me an email at liz@thecorporatecounsel.net.
Yesterday, the SEC posted a settlement of an administrative action relating to a bribery scandal that has been the topic of shareholder derivative litigation and DOJ enforcement (with the politician who was involved now serving a 20-year prison sentence). In its bite at the apple, the Commission’s enforcement claims were based on:
– False & misleading statements – that the company acted properly and ethically with respect to its political contributions
– Failing to disclose related-party transactions – because the company made payments to a 501(c)(4) that, while appearing independent on paper, was controlled by company executives
– Inadequate disclosure controls & procedures – the company’s accounting records did not correctly describe the payments as illegal or reflect them as related party transactions
The company settled the SEC’s claims for $100 million. While this situation was egregious, it’s a reminder that if “crisis communications” aren’t accurate, they can end up deepening the crisis – a violation of “Dave’s First Law of Holes.” Check out my blog from last year about reducing risks associated with corporate political spending.
I shared a few trends last month about newly filed insider trading policies. This Gibson Dunn blog adds observations from the 49 S&P 500 companies that were required to comply with the new “Exhibit 19” requirement as of June 30th (remember that for calendar-year companies, the new exhibit is first required with the Form 10-K to be filed in spring 2025). Here are 12 key takeaways:
1. Who’s Subject to the Policy: In addition to covering all company directors & personnel, and their family members, 82% expressly state that they apply to legal entities whose transactions are controlled or influenced by company personnel.
2. Gifts: 61% prohibit gifts when an insider as MNPI and/or apply the blackout & pre-clearance restrictions to gifts, and 8% restrict gifts only if the donor has reason to believe the donee will sell while the donor has MNPI. Of the policies that do not apply gift restrictions to all employees, a majority restrict gifts only for certain covered persons that are subject to additional restrictions, such as blackout periods and/or pre-clearance procedures.
3. Options: 69% exempt exercises of options when there is no associated sale on the market; however, exercises of options where there is a sale of some or a portion of shares delivered upon exercise (e.g., cashless broker exercise) are typically treated like any other sale.
4. Other Equity Awards: 59% exempt vesting and settlement of equity awards, such as RSUs and restricted stock, and 51% of the policies specifically provide that withholding of shares for tax purposes (i.e., net share settlement) is exempt.
5. Shadow Trading: 82% prohibit trading in the securities of another company when the person is aware of MNPI about such company that was learned in the course of or as a result of the covered person’s employment or relationship with the company. The remainder of the policies apply the prohibition more broadly to trading in the securities of another company while aware of MNPI about that company, without specifically addressing how the information was learned.
6. Who’s Subject to Blackouts/Windows: 88% subject directors, executive officers and a designated subset of employees to regular quarterly blackout periods, with a few policies applying two different blackout periods to different groups of employees.
7. Blackout Dates: The start date of the quarterly blackout periods ranges from quarter end to four weeks or more prior to quarter end. Under almost half of the policies (45%), the quarterly blackout periods start approximately two weeks prior to quarter end, 14% start the blackout periods three to four weeks prior to quarter end, and 18% start four weeks or more prior to quarter end. A significant majority of the policies (76%) end the quarterly blackout periods one to two full trading days after the release of earnings, with more policies ending after one trading day (51%) than two trading days (24%).
8. Pre-Clearance: For 65% of the policies, the preclearance persons are a subset of the persons subject to blackout periods, while for a minority of the policies (29%), they are the same as the persons subject to the blackout periods.
9. Other Prohibited/Discouraged Transactions: All of the policies prohibit or otherwise restrict certain types of transactions regardless of whether they involve actual insider trading. The most common prohibitions addressed: hedging transactions (96%);[8] speculative transactions (96%); pledging securities as collateral for a loan (90%); and trading on margin or holding securities in margin accounts (82%). A significant majority of the policies do not specifically address standing or limit orders or short-term trading, but of the ones that do, a significant majority take the approach of discouraging such transactions rather than strictly prohibiting them. Even where standing or limit orders are not strictly prohibited, some policies require that such orders be cancelled if the person becomes aware of MNPI (or prior to the start of a blackout period, if applicable).
10. Rule 10b5-1 Plans: All of the policies address the availability of Rule 10b5-1 plans. 71% describe the specified conditions under the SEC rules for a plan to qualify as a Rule 10b5-1 plan, although some do so in a more streamlined manner than others. Of these policies, a majority include Rule 10b5-1 plan requirements within the body of the policy, a minority do so in an appendix and one company filed the plan guidelines as a separate exhibit. 29% do not describe the specified conditions under Rule 10b5-1, but provide a general statement regarding the affirmative defense and refer covered persons to the officer administering the policy.
11. Company Transactions: Item 408(b) of Regulation S-K requires a public company to disclose whether it has adopted insider trading policies and procedures governing transactions in company securities by the company itself, and, if so, to file the policies and procedures, or if not, to explain why. Of the 23 S&P 500 companies subject to Item 408(b) that filed a Form 10-K and proxy statement prior to June 30, 2024, 78% did not address insider trading policies or procedures governing companies’ transactions in their own securities. Of the ones that did, most included a brief sentence or two about the company’s policy of complying with applicable laws in trading in its own securities. Only one company in our surveyed group filed a company repurchase policy as a separate exhibit.
12. Exhibit Filing: 88% of the companies filed only a single insider trading policy and no other related policies or documents (even where they referenced other related policies in their insider trading policy).
The blog notes that it’s still appropriate for specific provisions to vary from company to company. But when it comes to key policy terms that your insiders might ask about, it helps to understand “what’s market.” Make sure to check out our “Insider Trading” Practice Area for additional practical guidance.
This topic is also on the agenda at our “2024 Proxy Disclosure & Executive Compensation Conferences” – which are less than a month away! We’ll be sharing reminders for your next Form 10-K as well as practice pointers & trends. If you can’t make it to the Conferences in person, we also offer a virtual option. Register today by visiting our online store or by calling us at 800-737-1271.