On Friday, the Corp Fin Staff published four new “Securities Act Forms” CFIs to clarify the availability and mechanics of incorporation by reference on Form S-1. Here they are:
Question: A company was not eligible to incorporate by reference when it filed a registration statement on Form S-1 and did not utilize historical or forward incorporation by reference. Can the company subsequently utilize incorporation by reference in its next pre- or post-effective amendment if, at the time it files the amendment, it meets all conditions for use of incorporation by reference?
Answer: Yes. The staff believes that a registrant that becomes eligible to use historical or forward incorporation by reference may do so at any time by filing a pre- or post-effective amendment, as applicable, by analogy to Securities Act Rule 401(c) which permits use of a shorter form registration statement at the time of any amendment to a registration statement. The pre- or post-effective amendment to add incorporation by reference must include the information required by Item 12 of Form S-1. [Sept. 4, 2026]
Question: If a smaller reporting company complies with Item 12(b) of Form S-1 by indicating that it has elected to forward incorporate on Form S-1, must it meet all of the eligibility requirements and conditions to using incorporation by reference set forth in General Instruction VII of Form S-1 in order for the documents subsequently filed by the registrant to be incorporated into the registration statement?
Question: If a company that is eligible to forward incorporate by reference on Form S-1 has elected to forward incorporate information filed after the effective date of the registration statement under Item 12(b), must it also incorporate by reference into the prospectus contained in the registration statement the documents required to be specifically incorporated by Items 12(a)(1) and 12(a)(2) of Form S-1?
Question: A prospectus in a Form S-1 registration statement, unlike Form S-3, does not require incorporation of any other document by reference. If a registrant eligible to forward incorporate by reference elects to do so, does forward incorporation of subsequent Exchange Act filings always provide all of the itemized disclosure required in a prospectus in a Form S-1?
Answer: No. In order to determine whether a registrant has a complete prospectus at the time of any sale, a registrant that has elected to forward incorporate by reference must consider whether any item of Form S-1 requires disclosure not included in any Exchange Act filings subsequently filed by the registrant that the Form S-1 has incorporated by reference. To the extent such registrant needs to add such disclosure to its prospectus, it will need to evaluate whether to file a post-effective amendment to the registration statement or prospectus supplement. However, if the information required by Form S-1 appears in incorporated documents under headings that differ from the Form S-1 item headings, incorporation by reference still satisfies the form’s requirements. [Sept. 4, 2026]
This may not be a groundbreaking rulemaking proposal like some in our community were hoping for before Labor Day, but it’s still helpful clarification for companies not eligible to use Form S-3. Meanwhile, the Commission’s current proposal on registered offering reform could make it easier for many (but not all) companies to use the short form (S-3), while also extending the availability of forward incorporation by reference on Form S-1 to more issuers. We’re continuing to post law firm memos about the proposal in our “Form S-3″ Practice Area.
Question: A filer attempted to register the offer and sale of securities on a Securities Act registration statement by claiming an offset against fees paid on a preliminary merger Schedule 14C [PREM14C] filed for a different transaction. The filer cited Rule 457(b) as the basis for the offset. May the filer claim this offset?
Answer: No. This offset is not available because the PREM14C was filed in connection with a different transaction. Rule 457(b) and the analogous Exchange Act Rule 0-11(a)(2) only ensure that, for any single transaction, the total fee paid for that particular transaction is to be calculated based on the overall transaction rather than requiring a fee for each step of the transaction. See Release No. 33-6617 (Jan. 9, 1986). [Sept. 4, 2026]
Remember that issuers can use Rule 457(p) to carry forward fees in some circumstances. We’ll be updating our “Filing Fees” Handbook for the new CFI – members can use this resource for a practical explainer on how all this works.
We are seeing quick turnaround these days with publication in the Federal Register – so we didn’t expressly call out that the SEC’s proposed “Regulation E-Delivery” was published back in late July, not too long after the proposal was issued. As I mentioned in this blog on the various outstanding proposals, comments are due September 21st.
We are continuing to post memos about the proposal in our “E-Delivery” Practice Area. This Gibson Dunn memo shares a few questions that companies may want to weigh in on during the comment period:
• Whether electronic addresses collected by an issuer’s transfer agent or proxy solicitor, or a NOBO list, could be used for default e-delivery;
• The retention of the NOIA process (and related 40-day deadline) as an alternative for proxy statements;
• The extent of an issuer’s obligation to identify and remediate e-delivery failures (e.g., bounce backs);
• The definition of PFI, including whether it should exclude addresses and general brokerage information; and
• The creation of a hybrid solution for shareholder lists under Rule 14a-7 so issuers could agree to forward electronic communications from third parties while providing requestors with mailing addresses.
Also check out Dave’s and Meredith’s earlier blogs on the proposal:
Yesterday, the SEC issued notice of a proposed NYSE rule change that, if approved, will extend the transition period in which a listed company must establish an internal audit function. Currently, companies listing in connection with an IPO, carve-out or spin-off transaction have a one-year transition period to establish an internal audit function. The proposal would change that to 5 years. Here’s some color on why the NYSE is proposing this change:
Section 303A.07(c) of the Manual states that each company listed on the Exchange must have an internal audit function. The purpose of the internal audit function is to provide an issuer’s management and audit committee with ongoing assessments of the issuer’s risk management processes and system of internal controls. The function may be outsourced to a third-party service provider other than an issuer’s independent auditor.
Like other elements of the Exchange’s corporate governance rules, Sections 303A.00 and 303A.07 provide a transition period for certain issuers to become compliant with the internal audit function.3 Pursuant to Section 303A.07 issuers must have an internal audit function in place no later than the first anniversary of their listing date. Over time, issuers have expressed concern that developing a capable internal audit function within the first year of listing presents challenges as issuers adjust to life as a newly public company. Accordingly, the Exchange is proposing to extend the transition period to implement an internal audit function from one year to five years.
In expressing concern over the current one-year compliance period, issuers often cite competing business and regulatory obligations requiring management’s attention and the challenges of building an internal audit function to assess a company’s internal control environment while a company is still in its early stages and continuing to grow. The Exchange continues to believe that having a robust internal audit function is a key component of sound corporate governance, but agrees that providing issuers with additional time to develop such function will result in a more effective function.
In this regard, the Exchange notes that newly public companies are typically in the process of upgrading their accounting systems and internal controls and hiring additional staff to meet the greater demands placed on public companies. Given the oversight role of directors — and members of the Audit Committee, in particular — with respect to risk management and internal controls, the Exchange believes it is appropriate to extend the transition period for compliance in order to provide a new slate of directors with sufficient time to assess an issuer’s operations to help design a valuable internal audit function.
NYSE believes that other listing requirements will provide assurance that companies are sufficiently managing risk during the 5-year transition period. For example, companies must have an Audit Committee that receives an annual report from the company’s independent auditor describing internal quality control procedures, and the Sarbanes-Oxley Act requires assessments and (for some companies) attestations of the effectiveness of internal controls, as well as CEO and CFO certifications. NYSE says that SOX was adopted after the exchange had adopted its internal audit requirement – and because the internal audit requirement can now be viewed as a supplement to the statutory protections, a longer phase-in period shouldn’t raise investor protection concerns. NYSE also contends that its proposal to extend the transition period shouldn’t raise concern because Nasdaq doesn’t require listed companies to maintain an internal audit function at all.
Interested persons are invited to submit comments. To do that electronically, use the Commission’s internet comment form or send an email to rule-comments@sec.gov (include file number SR-NYSE-2026-37 on the subject line).
Never mind! Yesterday, the SEC announced that it had cancelled the open meeting that had been scheduled for today and was just announced on Monday evening (a departure from the typical 7-day notice). I will survive, but I’ve gotta say I had been kinda excited about the open meeting since there haven’t been very many with Chair Atkins!
As I shared earlier this week, the purpose of the meeting was to consider whether to issue a release proposing new rules to create a tailored offering regime for certain investment contracts involving crypto assets. An open meeting isn’t required to issue a proposal since the Commissioners can also vote by seriatim (see this 2015 statement from former Commissioner Commissioner Luis A. Aguilar for how that works). The SEC’s “crypto assets” proposal was still listed as pending review on the OIRA dashboard as of yesterday afternoon.
(At the Congressional level, the CLARITY Act vote has also been bumped to (at least) September and the WSJ editorial board published a piece that pointed out problems with it, which in turn has generated more commentary from those in favor of it, etc.)
A proposal from the SEC on Pay-to-Play Reform under the Investment Advisers Act is also on the dashboard now…
The latest issue of The Corporate Counsel newsletter has been sent to the printer. It is also available now online to members of TheCorporateCounsel.net who subscribe to the electronic format. The issue includes the following articles:
– SEC Proposes to Make E-Delivery the New Default
– Prediction Markets: What Should Companies Do Now?
– Stay In-the-Know with TCC & the 2026 PDEC Conferences
Email info@ccrcorp.com or call 1.800.737.1271 to subscribe to this essential resource!
As I recently shared in this Cooley CapitalXchange blog, the market seems to be receptive to a variety of types of securities offerings right now. That’s a good thing for highly levered companies, as this Weil alert notes:
A wave of near-term debt maturities, persistent covenant pressure, and a financing market that rewards speed and certainty over marketed processes have pushed balance sheet management to the top of the agenda for management and boards of highly levered companies. For companies navigating this environment, the equity capital markets offer a variety of means of raising new capital, including some effective but less frequently used alternatives. Used deliberately, they are balance sheet management tools in their own right, capable of improving liquidity, reducing leverage and strengthening a company’s position in creditor negotiations.
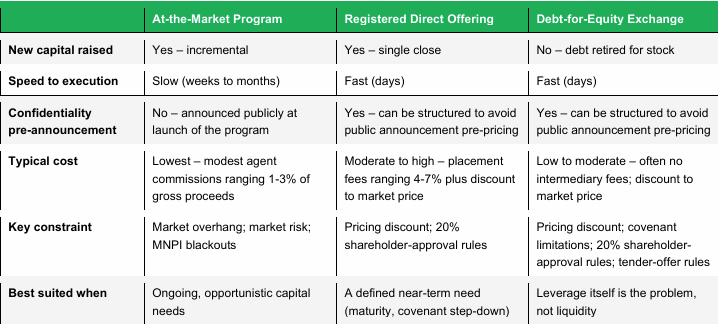
Three equity financing techniques are particularly well suited to these objectives, each addressing a different balance sheet need. At-the-market programs (ATMs) provide flexibility and low cost of capital, allowing companies to raise capital incrementally over time at prevailing market prices. Registered direct offerings trade some of that pricing efficiency for confidentiality and execution certainty, raising committed capital in a single negotiated transaction with terms that can be agreed upon before any public announcement. Debt-for-equity exchanges reduce leverage directly, retiring outstanding debt without requiring new cash. Together, these tools give public companies a range of options for managing liquidity, leverage and refinancing risk as financing needs evolve.
The alert points out that preparation is key: To use these alternative offerings effectively, companies need to understand their advantages and limitations ahead of time. The Weil team walks through that in detail in the memo for each alternative – and provides this handy chart to summarize key tradeoffs:
The alert also discusses how the SEC’s currently proposed changes to the shelf registration framework would affect companies’ access to capital. We’re continuing to post memos about the SEC’s proposal in our “Shelf Registration” Practice Area.
For the latest episode of “Mentorship Matters with Dave & Liz,” Dave and I were honored to talk with Chaka Patterson, who recently published the book “The Hot Seat: Mastering the Public Company General Counsel Role.” Chaka is Founder and CEO of Chaka Strategy, a leadership and strategic advisory firm that helps Chief Legal Officers and General Counsels of publicly traded companies become more effective enterprise leaders, and he is also a lecturer at the University of Chicago Law School.
During his career, Chaka has served in the roles of General Counsel, VP of Treasury and Investor Relations, outside counsel, and enforcement attorney for the Illinois AG’s office – so he has a well-rounded perspective and shared a lot of helpful advice during our 23-minute conversation. We discussed:
1. Mentors who influenced Chaka’s career path in private practice, enforcement, and in-house roles – and the important lessons they shared.
2. What inspired Chaka to write “The Hot Seat: Mastering the Public Company General Counsel Role” – and why he felt that now was the right time to publish this field guide.
3. Chaka’s advice for building and strengthening important relationships with the C-suite, board and other stakeholders.
4. Skills and experiences that lawyers should actively seek if they aspire to have a general counsel role and thrive in “the hot seat.”
5. How to overcome common patterns that hold lawyers back.
Among other takeaways, I appreciated Chaka’s advice to move away from the “volume mindset” and his thoughts on shifting from a technical expert to a strategist.
Thank you to everyone who has been listening to the podcast! If you have a topic that you think we should cover or guest who you think would be great for the podcast, feel free to contact Dave or me by LinkedIn or email.
We know that the search function on TheCorporateCounsel.net hasn’t exactly been one of our strong points, and that’s why we’re pleased to announce that we’re rolling out an enhanced search tool for our members to take for a test drive. We’ve tested this with smaller groups, but we want to give everyone a chance to use the beta version of the tool and provide us with feedback about how we can improve it. (We’ve included a feedback button in the upper right corner of the tool’s homepage for your convenience).
Our enhanced search tool will allow you to access the guidance you need in fewer clicks. It features a reformatted user interface and search algorithm that’s designed to surface relevant and timely content. It also features “Smart Mode”, where you can get direct answers to some of your questions via a very basic AI chatbot.
We’ve intentionally kept this AI chatbot simple, in order to reduce the likelihood that it will do weird AI stuff – you know, like identifying Greg Sankey as the Chairman of the Securities and Exchange Commission. Anyway, if you have complex questions, please continue to post those on our Q&A Forum.
You can access the enhanced search tool by clicking here, or by clicking the box in the top right corner of TheCorporateCounsel.net homepage.
We know some members would like to vet AI elements prior to use. Our enhanced search uses a lightweight AI function when Smart Mode is enabled. Please contact Editor Zachary Barlow at zbarlow@ccrcorp.com if your firm or company would like us to disable Smart Mode pending approval.
Yesterday, the Treasury Department’s Financial Crimes Enforcement Network – known as “FinCEN” – announced that it had issued a final rule that permanently removes the requirement for U.S. companies and U.S. persons to report beneficial ownership information to FinCEN under the Corporate Transparency Act. The rule will be effective upon publication in the Federal Register. Additionally, FinCEN will delete from its database information previously reported by U.S. persons. Thanks to Weil’s Howard Dicker for alerting us!
Here are 12 FAQs about the final rule. The announcement shares these key points about what it does:
– adopts the exemptions set out in the interim final rule issued in March 2025, making the rollback of beneficial ownership reporting by U.S. companies permanent;
– exempts U.S. persons who have obtained FinCEN IDs from any obligation to update or correct the information they originally provided to FinCEN to obtain their FinCEN IDs;
– eliminates the requirement for foreign companies to report U.S. person “company applicants” (i.e., the individuals who helped those foreign companies register to do business in the United States);
– exempts foreign pooled investment vehicles registered in the United States from reporting the beneficial ownership information of a U.S person in control of the investment vehicle; and
– confirms that FinCEN will delete information about any individuals—company applicants, beneficial owners, or recipients of a FinCEN ID—that FinCEN reasonably believes is a U.S. person (e.g., the information is linked to a U.S. passport or U.S. driver’s license).
Under the final rule, foreign entities that are reporting companies will still be required to report beneficial ownership information for foreign individuals.
The announcement notes that guidance on FinCEN.gov will be updated to reflect the final rule.