If the SEC repeals Rule 14a-8, the states are going to have some big shoes to fill when it comes to establishing rules governing stockholder proposals. Yesterday, the Delaware Corporation Law Council took the first step in that direction when it issued a White Paper on the controversial topic of precatory stockholder proposals along with draft legislation setting forth the limited circumstances under which those proposals would be permitted.
This Gibson Dunn blog summarizes the key provisions of the draft legislation, which would add a new Section 214 to the DGCL:
– Covered companies. Section 214 would apply only to listed companies with a market capitalization of at least $30 billion, measured as of the tenth day before the notice record date for the prior year’s annual meeting. Stockholders of smaller listed companies and of private companies would not be able to submit precatory proposals, and newly public companies would have a five-year grace period before precatory proposals would be permitted.
– Number of precatory proposals. Companies would be required to allow stockholders to submit and include in the company’s proxy materials (i) up to three precatory proposals in the aggregate at companies with a market capitalization of $100 billion or more, (ii) up to two precatory proposals at companies between $50 billion and $100 billion, and (iii) one precatory proposal at companies between $30 billion and $50 billion.
– Eligible proponents. A proponent would need to beneficially own (i) at least $250,000 in market value of voting stock individually, or (ii) together with up to nine co-filers, at least $1 million in market value of company stock, in each case held continuously for 365 days as of a date 30 days before the submission deadline. A stockholder could be the proponent or co-filer of only one proposal per meeting.
Directors, officers and persons acting for them would not be eligible for proponent or co-filer roles for these purposes (meaning their ownership would not count toward the caps). If more than the permissible number of precatory proposals are submitted and not otherwise excluded, the eligible proponents (together with their respective co-filers) owning the greatest number of shares would be allowed, with ties broken by random selection.
– Timing and content. Proposals would need to be received at least 180 days before the anniversary of the prior year’s annual meeting (subject to adjustment if the meeting date is advanced by more than 30 days), and, consistent with current Rule 14a-8, the proposal and any supporting statement together could not exceed 500 words. Again, similar to the current Rule 14a-8 process, a proponent would receive a single 14-day opportunity to cure deficiencies in its submission materials or word count.
– Bases for exclusion. The Discussion Draft lists 12 bases for exclusion, most of which are borrowed from Rule 14a-8’s procedural or substantive requirements, including (i) late or incomplete submissions, (ii) excess length, (iii) failure to meet the ownership requirements, (iv) a proposal that expressly questions the character of a director nominee, (v) a proposal that primarily seeks to redress a personal grievance, and (vi) a proposal that “no rational person would determine” is relevant to the company.
A resubmission bar would apply to a proponent where the same proponent submitted a proposal at either of the two preceding annual meetings at which precatory proposals could be presented and that proposal received less than 15% of the votes cast. The Discussion Draft does not authorize exclusion based on ordinary business, substantial implementation, violation of law or the lack of power to implement, or false and misleading statements.
– Proxy placement and presentation. If the company solicits proxies, up to the number of permissible proposals would be required to be included in the company’s proxy materials and on the company’s form of proxy. The company could include a statement in response or opposition and would be required to state that the proposal and supporting statement are solely the responsibility of the proponent.
The White Paper also provides that the company and its directors and officers would not be responsible under Delaware law for the proponent’s statements. As under Rule 14a-8, no vote would be taken on a precatory proposal unless the proponent or its proxy holder attends the meeting and requests a vote or the person presiding over the meeting submits the precatory proposal for a vote.
– Disputes. Only the proponent, and not a co-filer, could challenge the company’s determination that a proponent or proposal fails to satisfy Section 214’s requirements.
– Private ordering. Charters and bylaws could neither add to nor reduce the statutory requirements. In addition, a stockholder proposal could not request that the company adopt a charter or bylaw provision or policy that would provide for the inclusion of precatory proposals in company proxy materials outside Section 214.
Binding proposals would not be subject to the limits set forth in Section 214. Stockholders could continue to present and solicit proxies in support of any binding proposal addressing proper subject matter under Delaware law. Binding proposals could be subject to reasonable advance notice bylaws, and the company would not be required to include them in its proxy materials unless required by federal law. The draft legislation provides that it would become effective upon repeal of Rule 14a-8.
With Nasdaq and NYSE’s moves to 23×5 trading set to kick off next month, this Skadden memo offers guidance for public companies on issues they should keep in mind. This excerpt discusses the potential implications of 23/5 trading on insider trading and other corporate policies:
Consider whether existing insider trading policies and trading window procedures require amendment in light of the new overnight session. For companies listed on the New York Stock Exchange, whose policies are tied to the preserved Core Session (9:30 a.m. to 4 p.m. ET), the overnight session may require little or no policy change. For Nasdaq-listed companies, the consolidation of pre-market, regular and post-market hours into a single Day Session (4 a.m. to 8 p.m. ET) may shift the meaning of policy terms like “market hours,” “market close” and “trading day.” Those companies should consider whether their insider trading policies and trading windows should reference specific hours rather than exchange-defined sessions.
Nasdaq-listed companies also should consider reviewing other corporate policies and equity plans that reference exchange-defined sessions, which may have shifted under Nasdaq’s consolidated two-session structure. For instance, it may be advisable for companies to clarify how certain aspects of
their equity plans or policies will be interpreted in light of 23×5 trading, particularly for Nasdaq-listed companies’ equity plans that reference exchange-defined sessions (e.g., using “closing
sales price” in the Fair Market Value definition).
Other issues that the memo says public companies need to consider include the implications of longer trading days for disclosure practices, including press releases and SEC filings, whether definitional provisions in contractual arrangements need to be modified for the new environment, and how extended trading hours may impact the way capital markets transactions are structured.
Tomorrow is Veterans Day, and on behalf of everyone here at CCRcorp, I’d like to express our sincere thanks to all who served our nation. Here’s a blog I posted on the 75th anniversary of D-Day over on the John Tales Blog on DealLawyers.com that I thought might be appropriate for today:
Forgive me this departure from the law-related stuff, but since this week is the 75th anniversary of D-Day, I wanted to share a remarkable story that I heard when my wife and I visited Normandy a few years ago.
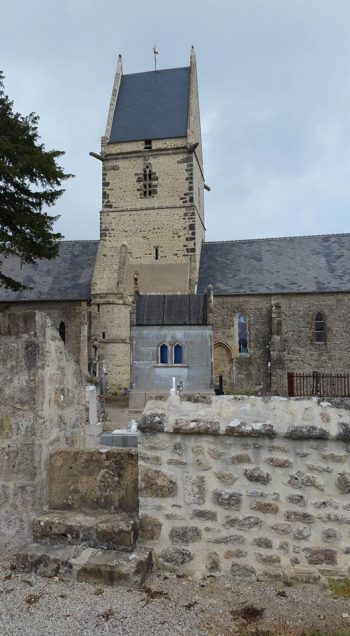
We spent a couple of weeks in France in 2016, and saw so many beautiful sites that I honestly can’t remember them all. But I’ll never forget this nondescript little church on the outskirts of a postage-stamp sized town in Normandy called Angoville au Plain, a few miles inland from Utah Beach. It’s a place that most D-Day tours don’t visit, but we had a very small group that day, and our guide decided to take a little detour to visit “her favorite site.”
From June 6 to June 8, 1944, Angoville au Plain was fought over constantly and changed hands several times. When the Americans first took it on D-Day, they set up an aid station inside this church. The pews remain blood stained to this day.
When the Germans counter-attacked, it became apparent that the Americans were going to have to retreat. Many of the wounded couldn’t be moved, and the two medics running the aid station – Robert Wright and Kenneth Moore – refused to pull out and leave them behind. Their commander agreed to let them stay.
The Germans arrived shortly after the Americans pulled out. When they did, they saw the medics tending to the wounded and carrying them into the church. The German commander asked if they would treat the German wounded too. They said that they would, and he let them carry on with their work.
Soon, wounded German soldiers found their way to the church. The only condition Wright and Moore imposed was that they leave their weapons outside. At one point, German soldiers on patrol stumbled into the church. They pointed their weapons at Wright and Moore, but when they saw they were treating both U.S. and German soldiers, they backed out, and had a red cross flag placed next to the door.
During the first night, a battle raged in the church yard. Although the church was once hit by a stray shell, throughout the fight, the Germans and the Americans respected the neutrality of this site, and these two medics treated 80 wounded American and German soldiers, along with a French child. Only two of the people they treated died.
The 101st Airborne finally took the town for good on June 8th. Kenneth Moore and Robert Wright were both awarded the Silver Star for gallantry. Moore was 20 years old. Wright was 19.
Enjoy the holiday. Our blogs will be back on Thursday.
Last week, Senators Elizabeth Warren (D – Mass.) and Chris Van Hollen (D – Md.) sent an 8-page letter to SEC Chair Paul Atkins asking the agency to reconsider its recent rulemaking proposals. In the title of this blog, I said that the senators sent Chairman Atkins their love with this missive. I should clarify that I meant that in the same way King George III did in Hamilton, when he told his rebellious subjects that he’d “send a fully armed battalion to remind you of my love. . .”
In their letter, the soon-to-be Chair of the Senate Banking Committee and her colleague fire a broadside at all of the SEC’s recent proposals to ease the regulatory burden on public companies. This excerpt from the first paragraph gives you a sense of the senators’ position and the overall tone of their correspondence:
Although you claim to want to “Make IPOs Great Again,” the SEC’s specific proposals to deregulate the public company registration and disclosure regime represent an unprecedented attack on investors’ rights to transparency from public companies and threaten to undermine investor protection and market integrity. Your broad deregulatory agenda would compromise the integrity of our capital markets at a moment when Americans are already reeling from spiraling costs and unprecedented corruption in the Trump economy. We urge you to rescind these recent proposals that would put families and investors at even greater risk.
As I said, the letter asks the SEC to reconsider all of these proposals, but I want to focus on the authors’ objection to the SEC’s efforts to promote IPOs through deregulation. The letter argues broadly that the dearth of IPOs isn’t the result of overregulation but instead reflects, among other things, the impact of deregulation of the private markets. The letter contains a bunch of footnotes citing academic studies supporting these arguments, but it also refers to the SEC several times as the “Security and Exchange Commission,” which doesn’t exactly enhance the letter’s credibility when it comes ideas about securities regulation.
The way the letter lays out its argument about the supposed deregulation of private markets as a cause of the decline in IPOs is a bit of a head scratcher. Here’s what the authors say:
Expanded opportunities to raise capital with less expense and oversight in the private markets has created a structural disincentive to going public. In other words, it is not that public markets are overregulated, it is that private markets are underregulated, and repeated deregulatory reforms have pulled more and more capital from the public markets into the private markets. Lighter regulatory requirements – such as no obligation to provide investors with financial statements, quarterly reports, material event reporting, or disclosure about executive compensation – have incentivized a growing number of companies to raise capital in the private markets rather than go public.
Really? Private companies have never been required to provide annual executive comp information or periodic reports to investors and have been able to offer securities privately without any specific disclosure requirements – at least in offerings involving accredited investors – ever since Reg D was adopted in 1982.
It’s hard to see how pointing out things that private companies have never been required to do or have been permitted to do for nearly 45 years supports claims that “repeated regulatory reforms” have incentivized issuers to stay private. The letter goes on to cite the rise in Reg D offerings in support of its argument, but that seems to me to confuse cause and effect when it comes to the lack of IPOs. To be fair, the studies that the letter cites make more sophisticated arguments, but this is the one that, for whatever reason, the authors chose to run with.
The policy concept here seems to be that instead of lightening the load on public companies, the way to bring back IPOs is to drive “underregulated” private companies into the public markets with the lash. That’s absolutely nuts, and the fact that the authors offer it up with a straight face only confirms what many suspect: a lot of policymakers on the left think that companies exist for the sole purpose of churning out disclosures to satisfy ever-expanding activist group demands and to provide grist for the academic tenure mill.
That’s too bad, because an agency like the SEC that has acted without any input from commissioners who disagree with its swashbuckling deregulatory approach for nearly two years is in dire need of sober-minded congressional oversight. But if this letter is an example of what we can expect, those oversight efforts are going to fall far short of the mark.
With the Democratic majority in both houses of Congress expected to take an aggressive approach to investigations, this Mayer Brown memo provides some guidance on whether a particular company is likely to be on the receiving end of an investigative subpoena. This excerpt highlights questions that companies that have interacted with the Trump administration should ask in assessing their risk of being targeted by Congress:
– Have interactions with the administration resulted in significant regulatory decisions, transaction approvals, exemptions, tariff relief, federal funding, or other benefits that could become the subject of congressional inquiry?
– Has the company entered into prominent commercial relationships or participated in initiatives that may attract political or public attention?
– Could internal communications, board materials, or other records be interpreted differently from the company’s public statements or explanations of its decisions?
– Are there issues involving government relationships, corporate conduct, or public policy that could become relevant to a broader investigation of administration actions?
The memo says that companies expecting possible congressional scrutiny should identify potential areas of exposure, ensure they can preserve and collect relevant records, and establish a coordinated, cross-functional response. Senior executives and directors should also be prepared for possible inquiries or testimony and a strategy for engaging with policymakers and managing internal and external communications should be developed.
By the way, if you represent a tech sector company – particularly one that’s played footsie with the Trump administration – be sure to check out this Fenwick memo on oversight topics that tech companies should expect to see inquiries from Congress about in 2027.
Latham recently published a summary of insights provided by senior congressional staff members on how congressional oversight has evolved and what private sector companies should consider when responding to congressional inquiries. This excerpt discusses the importance of early and cooperative engagement:
– Proactive outreach: Committees often send broad initial requests, either through a formal letter or informal email outreach. In many instances, early, constructive dialogue can narrow the scope of these requests and help clarify the focus of the inquiry. The panel stated that a helpful posture is for companies to use their government affairs resources to monitor committee priorities and anticipate potential activity so that, under appropriate circumstances, they can proactively reach out prior to formal requests.
– Responding to sector-wide letter “blitzes” requires a thoughtful approach: When congressional committees or individual members send a similar letter to many companies in the same industry, each company should carefully determine an appropriate response. Entities that do not respond or send incomplete responses stand out when others cooperate fully, potentially triggering follow-up. Companies should aim for timely responses, and should be aware that committees could analyze responses across sectors for indications of industry viewpoints or vulnerabilities.
The memo says that companies should integrate their government relations, communications, and legal functions in order to ensure an effective response to congressional oversight. It also cautions companies that when an administration tries to stiff-arm Congress on investigative demands, it often turns to private sector players to access the information it wants.
For a practical deep dive on the midterms, take a look at this Akin alert. At a high level, it says:
Democratic control of both chambers significantly shifts the policy environment during the final two years of President Trump’s term. With sizable majorities, Democrats will have greater ability to advance their agenda, particularly on affordability and oversight of the Trump administration. Their ability to enact major legislation will remain constrained by the Senate’s 60-vote threshold for most legislation and President Trump’s veto authority (requiring an override vote of 67 votes in the Senate and 290 votes in the House).
Democratic priorities are expected to center on affordability and accountability across several industries including health care, tax policy, international trade, artificial intelligence and data centers, energy, and financial services. Control of the Senate will also give Democrats authority over committees and the confirmation process for executive branch and judicial nominees. However, Democrats will still need Republican support to advance major legislation, placing greater importance on areas of potential bipartisan agreement and on appropriations, authorization bills, and other must-pass legislation as vehicles for policy changes. Specific proposals and sector impacts are discussed in greater detail in the Issues to Watch section below.
For the Trump administration, the loss of unified Republican control will all but eliminate the path to advancing President Trump’s legislative priorities. The administration is therefore likely to rely more heavily on executive and regulatory authorities, while potentially devoting greater attention to foreign policy, international trade, and national security. Divided government is unlikely to mean a quieter policy environment, with executive actions, regulatory changes, tariffs and trade measures, and congressional oversight among the key areas to watch.
Here are some highlights for public companies from the “Issues to Watch” section:
With Rep. Maxine Waters (D-CA) and Sen. Elizabeth Warren (D-MA) poised to chair the House Financial Services Committee and Senate Banking Committee, respectively, expect an agenda focused on consumer protection, corporate accountability, and heightened scrutiny of the Trump Administration.
Democrats will shift the committee agenda toward stronger consumer and investor protections, expanded regulation, and oversight of the Administration’s deregulatory agenda and financial institutions, including their climate and Diversity, Equity, and Inclusion commitments and ties to President Trump.
Democrats will intensify scrutiny of AI, bank mergers, executive compensation, shareholder buybacks, private equity ownership, expanded retail investor access to private markets, and market concentration, along with increased attention to nonbank financial institutions and broader financial stability risks.
With a stablecoin framework in place, Democrats will focus on implementation through a consumer protection and financial stability lens while pursuing additional digital asset guardrails addressing investor protection, conflicts of interest, and illicit finance.
The midterms didn’t just shake things up at the Federal level. We may also see major policy changes at the state level — particularly in Texas, where Democrats will take over the Governor, Lieutenant Governor and Attorney General offices, plus take control of the state house. That’s causing practitioners and academics to wonder what this means for the state, which has been a favored jurisdiction for companies reincorporating out of Delaware and the site of several recent stock exchange launches.
On LinkedIn, Law Prof Christine Hurt pointed out that Texas Business Court judges are appointed for only two-year terms, making those appointments potentially influenced by political winds. Law Prof Ann Lipton also noted that the new Democratic Attorney General may not pursue the state’s existing lawsuits against the proxy advisors or want to defend the proxy advisor law that is currently enjoined on a First Amendment basis.
We’re all questions and speculation today because none of us have a crystal ball, but asking the questions can be helpful to avoid being blindsided when current trends come to an abrupt halt or reverse course. To that end, the Cooley team has spent some time brainstorming how the midterm results might impact general trends and the SEC’s agenda, and on the Governance Beat blog, Broc shared 10 questions for companies to consider. For example:
– Many companies pulled back on DEI programs and disclosure in response to Administration pressure. Will those companies now face congressional scrutiny or otherwise feel pressure to reverse course?
– Even if SEC leadership remains unchanged, could a shift in Congressional control influence which rulemaking initiatives move forward, slow down or get abandoned
– How might the elections affect the SEC’s budget and staffing? Could Congressional appropriations, oversight hearings and staffing constraints influence the agency’s ability to conduct examinations, pursue enforcement actions and adopt new rules?
– Will cryptocurrency and tokenization face a different political environment? How might the new Congress approach digital asset market structure, tokenized securities, investor protections and the division of regulatory authority between the SEC and CFTC?
On Friday, Reuters shared takeaways from an interview with David Woodcock, Director of the SEC’s Division of Enforcement. His remarks were focused on AI-enabled fraud and AI-related disclosures, private markets and prediction markets. Here are some snippets:
The US Securities and Exchange Commission is examining artificial intelligence companies’ corporate disclosures as investor worries mount over a potential AI bubble that may have been fueled by circular deals, the agency’s enforcement director told Reuters on Friday [. . .] [T]he agency does not want to stand in the way of tech innovation, but that it is the agency’s job to ensure issuers are giving investors the full picture on potential risks.
Woodcock said the SEC also has a role in overseeing prediction markets [. . .] Woodcock said the agency’s enforcement staff are working with policy officials as well as the Commodity Futures Trading Commission, which broadly oversees swap markets, to monitor and regulate the booming new markets.
David Woodcock also spoke at Practicing Law Institute’s 58th Annual Institute on Securities Regulation yesterday. Here are a few highlights from his remarks, which you can watch on YouTube.
– The number of financial reporting and accounting cases had been down before the launch of the Financial Reporting and Accounting Unit, possibly because these cases take longer to investigate (over 4 years, on average) and are very complex, highly technical and judgment laden. The new unit is staffed with a specialized team of accountants and lawyers and meant to be durable. The types of cases they’re investigating are the same as always: e.g., revenue recognition, valuation issues and areas of accounting that require significant judgment.
– He noted that the Enforcement Division is trying to avoid pushing the envelope, from a legal perspective, on the claims they are pursuing (i.e., avoiding regulation by enforcement) and focused on being transparent while welcoming the perspective of the defense and its counsel so that the Commission can see their side.
– Enforcement Staff wants to give cooperation credit. He pointed to the recent enforcement action regarding the issuance of ESPP shares in excess of the number registered on Form S-8, which involved no civil penalty. (The company promptly suspended the ESPP, conducted an investigation, self-reported to the Commission and voluntarily initiated a rescission offer.) He suggested that companies carefully consider self reporting with their counsel because once a whistleblower reports to the SEC, cooperation credit becomes fuzzy. He stressed that the Staff doesn’t talk about instances where no charges were brought, but that does happen.