The Texas Stock Exchange (TXSE) began trading in July with a phased rollout, initially allowing equity securities of companies listed on other exchanges to trade on the TXSE as “unlisted trading privileges.” Now, the stock exchange is moving up in the world. Bloomberg reports:
Texas Capital Bancshares Inc. will switch its primary listing to the Texas Stock Exchange from Nasdaq, making it the fifth company in a week to jump to the upstart marketplace.
The Dallas-based financial services provider expects to begin trading on the new exchange on Oct. 8, according to a company statement Monday. The announcement came four days after pipeline operator Energy Transfer LP and three related companies said they would shift to the TXSE.
Those three related companies are Sunoco LP, SunocoCorp and USA Compression Partners LP. The article says Texas Capital’s CEO, Robert Holmes, serves on a TXSE advisory board, and Energy Transfer’s chairman, Kelcy Warren, is a backer of the exchange’s parent company, so all have some connection to the TSXE. But still, five companies just this week!
Hot tip for when you’re having conversations about this: TSXE is pronounced “TEX-ee”!
Be on the lookout for an email from us (CCRcorp) via no-reply@events.ringcentral.com (our conference platform and app provider) in the coming days. This email confirms your registration and contains your unique link to access the conference platform. (If you’ve never attended a RingCentral event before, you will also receive a second email confirming that a RingCentral account has been created for you.)
That unique link will give you instant access to the platform, where you can view the detailed conference schedule, location information, hotel maps, course materials and CLE forms. Our virtual attendees will also use this platform to join the conference livestream. It also has a chat feature that both in-person and virtual attendees can use to ask questions anonymously. We recommend accessing the platform either through the RingCentral Events app, which is available for download on both iOS devices or Android devices, or on a desktop browser. Virtual attendees are encouraged to stream the live conference on a desktop browser for the best experience.
If you haven’t registered yet, the clock is ticking! We’re less than one month out. Visit our online store, email info@ccrcorp.com or call our team at 800-737-1271 today. There’s so much to talk about, and with the pace of change, no doubt there will be even more to discuss by October. Our experienced speakers will be covering all the latest & greatest!
Companies have started addressing prediction markets in their corporate policies to manage the risk of employees trading on prediction markets on the basis of nonpublic information. (See Dave’s article for the July-August 2026 issue of The Corporate Counsel, “Prediction Markets: What Should Companies Do Now?”) Because prediction markets often do not involve “securities,” this may not be as simple as adding a line to your insider trading policy.
While there may not be a one-size-fits-all solution because each company will have to consider its existing policies to determine whether and how to revise them to reflect prediction market insider trading risk, data on what other public companies are doing can be helpful to have in your back pocket. To that end, this O’Melveny quarterly newsletter shares how companies have addressed prediction markets in their policies this year.
In 2026 through September 2, 2026, 54 companies (including 12 large companies) updated their publicly available codes of conduct and 30 companies (including 12 large companies) updated their insider trading policies to include prediction markets language.
Companies typically took a more restrictive approach to prediction markets than that which it applied to securities transactions generally, although this was more common in codes of conduct (81% of companies with prediction markets language in their codes of conduct) than in insider trading policies (69% of companies with prediction markets language in their insider trading policies).
– Prohibition on engaging in any prediction market transaction involving the company. Approximately 24% of companies that included prediction markets language in their codes of conduct restricted employees from engaging in any prediction market transaction involving the company. A similar number of companies included that prohibition in their updated insider trading policies, but due to the smaller number of filed policies containing prediction markets language, this constituted 41% of insider trading policies.
– Application of a lower standard for restricting participation in prediction markets. Approximately 56% of companies that included prediction markets language in their codes of conduct restricted participation based on a lower standard of information (possession of confidential or nonpublic information, rather than material nonpublic information), while 14% of companies that included prediction-markets language in their insider trading policies applied this lower standard. One company took a different approach in its insider trading policy and prohibited trading by individuals in event contracts where they had the ability to affect the outcome of the contract.
Of the 54 companies addressing event contracts in their publicly available codes of conduct, nearly half (46%, or 25 companies) included language regarding prediction markets in the section of their codes of conduct covering insider trading, while one-third of companies (33%, or 18 companies) included the language in the section of their codes of conduct covering confidentiality obligations. A significant minority of companies (15%, or 8 companies) included language regarding event contracts as a standalone section of their code of conduct. Companies also included prediction market language in the sections of their codes of conduct covering conflicts of interest (9%) or compliance with laws (4%).
Meanwhile, more than three-quarters of companies (76%, or 22 companies) that addressed prediction markets in their insider trading policies described trading in event contracts as distinct from trading in securities, often acknowledging that such trading may not be covered by traditional securities restrictions. Many of these companies included restrictions on trading in event contracts in the same section as other prohibited transactions, such as hedging and pledging of securities or entering into derivatives contracts.
The report emphasizes that this is an emerging and evolving risk area, so companies should monitor developments and may want to adjust their practices in response.
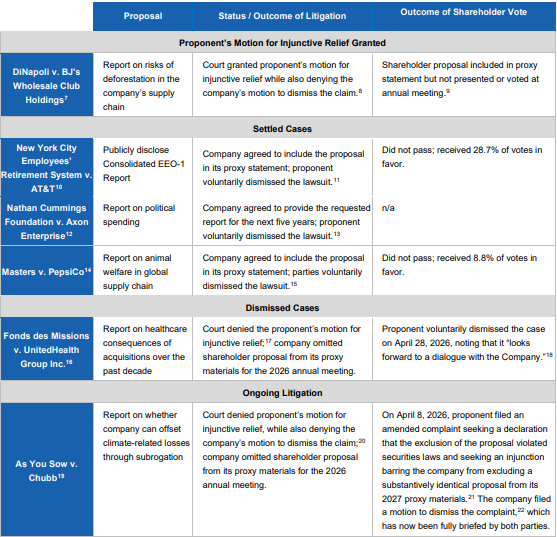
I had a hard time mentally keeping track of the litigation over the exclusion of shareholder proposals from proxy statements this proxy season (even though we were sharing updates here and on The Proxy Season Blog). So I was pleased to find this chart in the O’Melveny quarterly newsletter I shared in my first blog today covering all the litigation – with updates (even reflecting the vote on the shareholder proposals for those that were ultimately submitted to shareholders).
There is also litigation alleging that the change to SEC Staff’s involvement in the Rule 14a-8 process violated the APA. The newsletter has an update on that too:
The lawsuit is still at the motion for summary judgment stage. Although briefing was initially expected to be completed by the end of October 2026, on September 3, 2026, the court granted the parties’ joint motion to hold the litigation in abeyance while they determine how to proceed in light of Corp Fin’s August 2026 decision to permanently withdraw from its participation in the Rule 14a-8 no-action process.
It’s been a couple years since I’ve blogged about FASB’s initiative to require companies to quantify labor costs and other income statement expenses. Even though the SEC hasn’t moved forward with detailed human capital disclosure requirements, “public business entities” are still going to need to start providing employee compensation info in the notes to financials in response to FASB Accounting Standards Update 2024-03, which was adopted in November 2024. This Deloitte guide explains what ASU 2024-3 will require and what in-scope companies should do to prepare. Here are a few key takeaways (also see this FASB alert):
The DISE standard introduces new requirements related to disaggregating certain income statement expense captions within the footnotes to the financial statements. These disclosures are required for annual reporting periods beginning after December 15, 2026, and interim periods within annual reporting periods beginning after December 15, 2027.
The ASU does not change the expense captions an entity presents on the face of the income statement or the recognition and measurement principles of other GAAP standards; rather, it requires disaggregation of certain expense captions into specified categories in disclosures within the footnotes to the financial statements.
An expense caption presented on the face of the income statement within continuing operations is considered relevant and therefore subject to disaggregation if it includes any of the following natural expense categories:
(1) purchases of inventory;
(2) employee compensation;
(3) depreciation;
(4) intangible asset amortization; and
(5) depreciation, depletion, and amortization (DD&A) recognized as part of oil- and gas-producing activities or other types of depletion expenses.
Entities will need to disaggregate relevant expense captions into these five natural expense categories (the “required expense categories”) in a tabular presentation. The tabular disclosure for each relevant expense caption will also include certain other expenses and gains or losses that must be disclosed under existing U.S. GAAP (the “tabular integration of other disclosures”), expense reimbursements, and other expenses when applicable. The ASU does not change or remove existing expense disclosure requirements; however, it may affect where that information appears in the notes to financial statements because the ASU requires entities to include certain current disclosures in this tabular format.
The requirement applies to “public business entities,” which the standard defines as entities:
– Required by the SEC to file or furnish financial statements, or does file or furnish financial statements (including voluntary filers), with the SEC (including other entities whose financial statements or financial information are required to be or are included in a filing).
– Required by the Securities Exchange Act of 1934 (the Act), as amended, or rules or regulations promulgated under the Act, to file or furnish financial statements with a regulatory agency other than the SEC.
– Required to file or furnish financial statements with a foreign or domestic regulatory agency in preparation for the sale of or for purposes of issuing securities that are not subject to contractual restrictions on transfer.
– That have issued, or is a conduit bond obligor for, securities that are traded, listed, or quoted on an exchange or an over-the-counter market.
– That have one or more securities that are not subject to contractual restrictions on transfer, and it is required by law, contract, or regulation to prepare U.S. GAAP financial statements (including notes) and make them publicly available on a periodic basis (for example, interim or annual periods). An entity must meet both of these conditions to meet this criterion.
An entity may meet the definition of a public business entity solely because its financial statements or financial information is included in another entity’s filing with the SEC. In that case, the entity is only a public business entity for purposes of financial statements that are filed or furnished with the SEC.
The ASU does not apply to a not-for-profit entity nor an employee benefit plan.
The Deloitte guide points out that in-scope companies should prepare now for these disclosures, because they may need to collect underlying data may not currently be readily available beginning in 2027 (for calendar year companies) – and companies may need to consider estimates, information systems and reporting changes, and adjustments to processes and controls. The nature and extent of new information required are expected to vary by entity and industry – as illustrated in this separate Deloitte alert for consumer products and retail companies.
From a governance standpoint, this update obviously affects audit committees – and hopefully they are already discussing it. But as Meredith recently blogged, human capital is still on the agenda for many compensation committees as well. Comp committees may want to think ahead about how this new data will be presented and used – by the committee itself as well as other stakeholders.
When the SEC announced that it had entered into a cooperative Memorandum of Understanding with the FDA to facilitate information sharing to improve the agencies’ regulatory and enforcement responsibilities, I think many practitioners were wondering whether this was a formalization/codification of current practices or an expansion of cooperation, how the MOU would change the agencies’ current communication in practice and what it means for life sciences companies. This Goodwin alert gives us the lowdown.
Interagency cooperation between the SEC and FDA is not new. In 2004, the agencies announced a collaboration to make referrals and exchanges of nonpublic information more efficient, relying on designated contacts and existing statutory and regulatory authorities. The SEC Enforcement Manual (the “Manual”) describes the resulting process. Staff considering a request to the FDA were expected to consult supervisors, notify the Division of Enforcement’s FDA liaison, and assess the statutes governing FDA disclosure. The Manual cautions, however, that requests should be tailored, that substantial time should be allowed for FDA review, and that the company’s consent to further disclosure of its confidential commercial information should be sought early.
The MOU does not “create enforceable rights or obligations” but should improve consistency by establishing certain contacts and procedures to be followed when sharing nonpublic information
Standing channels and accountable contacts. Each agency is to establish a mechanism to receive requests and a secure means to transmit nonpublic information. The SEC’s principal contacts include representatives from the Division of Enforcement and the Division of Corporation Finance; the FDA’s include a representative from the Office of the Chief Counsel.
A defined request-and-response process. A request must describe the information sought and its intended use, be signed by an authorized official, and, for SEC requests, include the required nondisclosure assurance. The agencies commit to timely responses and may develop standard operating procedures and model templates.
Express use in filing reviews and enforcement matters. The MOU confirms that the SEC may use nonpublic FDA information in public company filing reviews and in enforcement investigations and resulting enforcement actions. Including the Division of Corporation Finance is significant: FDA information may influence disclosure review before or apart from an enforcement investigation, and a filing-review issue can lead to an enforcement referral.
Two-way sharing with confidentiality safeguards. Consistent with statutory and regulatory limitations on the ability of the SEC and the FDA to share information with other agencies, the MOU provides that both agencies must restrict access to personnel who need the information, preserve applicable privileges, and coordinate on third-party demands. The providing agency retains a central role in responding to Freedom of Information Act requests, subpoenas, and other efforts to obtain shared material, and the SEC must also obtain permission from the FDA before sharing non-public materials obtained from the FDA with third parties.
Important limits remain. Although the FDA may refer potentially violative conduct to the SEC, the MOU does not authorize the FDA to share with the SEC information that governing statutes prohibit it from disclosing. For example, Section 301(j) of the Federal Food, Drug, and Cosmetic Act restricts disclosure of proprietary manufacturing methods or processes contained in drug applications or FDA inspection materials. The MOU also does not cover public information, testimony requests, or subpoenas, and it does not govern requests made before August 31, 2026.
While I bet most life sciences companies were aware or assumed that the Division of Enforcement was able to get nonpublic information from the FDA, I also bet that more life sciences companies were not aware that Corp Fin is part of this information-sharing process and that information provided by the FDA may result in a comment during a filing review by the Disclosure Review Program. That doesn’t necessarily change things for public companies — this MOU does not create any new public company obligations, and most life sciences companies already have disclosure controls in place to validate their public statements against regulatory correspondence to ensure their disclosure is accurate, complete and not misleading — but it’s good to be aware of.
On the enforcement side, the alert highlights an important point about the Wells process. As it notes, the SEC has recently worked to improve transparency in the Wells process, but that transparency may not always be able to extend to information provided to the Enforcement Staff by the FDA.
Under the MOU, the SEC may more easily obtain nonpublic FDA information, but it may not disclose that information outside the agency without the FDA’s written permission. The MOU provides that the FDA will respond promptly to permission requests, but obligates the FDA to grant permission only when disclosure is compelled by law or judicial order. The result is a potential information gap at the most important pre-charge stage. The SEC staff may know that the FDA record undercuts a company’s public account while the Wells recipient sees only a description of the evidence, selected nonrestricted material, or documents already in the recipient’s possession. The problem may be most acute for individuals who do not control the company’s complete FDA file, or when FDA records contain third-party information or require extensive review before the agency will authorize access.
The MOU also does not specify how the SEC should proceed if the FDA declines or delays permission, whether the SEC staff should segregate FDA materials from the Wells file, or how much detail staff should provide about information it cannot share. Counsel representing life sciences companies and their executive officers should raise access issues early: Identify the FDA materials likely to be relevant, ask what FDA-originated information the staff considered, and request that the SEC promptly seek FDA permission to share materials in the Wells file.
This summer, the Center for Political Accountability (CPA) and the Wharton School announced the joint release of a research primer that addresses the risks that corporate political spending may pose to companies and ways companies can improve the transparency, accountability, risk management and alignment with messaging when it comes to political spending activities. I’ll freely admit that I find this space very confusing — with all the different terms and types of entities that are used to pool money and resources — but I try not to fault myself for feeling a bit lost because I assume it’s confusing by design so that the parties involved can keep the details of donations private if and until they choose to disclose them. What I didn’t appreciate, though, is that the confusing design that seems like it might benefit a sophisticated corporate donor may actually work against it.
That’s because it may not actually keep donations private. We know from news reports that “[p]olitical spending that companies expected would never become public has.”
It can also present risks to those corporate donors because they have less control over the ultimate recipient or cause their spending supports when they give to third-party groups that may “use the companies’ funds for a wide variety of political support, often without informing corporate donors of the details of their activities.”
When companies decide to make political donations, they may attempt to donate to causes or candidates they believe reflect the core values of the company. Yet the reality is that once the money goes into a third-party group, firms lose all control of their donations [. . .] In many cases, corporate donations may be transferred from the original recipient to additional third-party groups before being spent on an election. This process can obscure the ultimate destination of funds both to the detriment of firms who donate [. . .] They end up supporting any and every endeavor of the recipient and its affiliattes—which means that firms may donate to campaigns or causes misaligned with their stated values or the values of their stakeholders. Such misalignment poses a very real threat to a firm’s reputation.
The primer suggests that companies ask themselves the following key questions before moving forward with political spending:
– Can a strong case be made that the spending advances the corporation’s key business objectives?
– Does the spending threaten the company’s reputation or expose it to unnecessary risks?
– Regardless of legal risks, is this kind of spending ethical?
The latest issue of The Corporate Executive newsletter has been sent to the printer. It is also available now online to members of TheCorporateCounsel.net who subscribe to the electronic format. The issue includes the article “A Season of Change: What We Learned from the 2026 Proxy Season,” in which Dave shares his thoughts on some of the trends that shaped the 2026 proxy season and practical suggestions for navigating this time of significant uncertainty and change.
Email info@ccrcorp.com or call 1.800.737.1271 to subscribe to this essential resource!
You can still register for our popular conferences – the “2026 Proxy Disclosure & 23rd Annual Executive Compensation Conferences” – to be held in person in Orlando and virtually nationwide on Monday, October 12th – Tuesday, October 13th. With so much rulemaking and guidance coming out of the SEC right now, you won’t want to miss hearing practice pointers and strategies to track what might change – and how to implement new frameworks.
For more details, check out the agenda – we’ll kick things off with a conversation with Christina Thomas, who is Deputy Director of the SEC’s Division of Corporation Finance & Chief Advisor on Disclosure, Policy, and Rulemaking. From there we’ll dive into proxy season insights, the fate of shareholder proposals, the shareholder activist landscape and more. Our speakers are fantastic and this is truly a “can’t miss” event for anyone involved with proxy disclosures, corporate governance, and executive pay.
Conference attendees will not only get access to our unique & valuable course materials – you’ll also get access to the conference archives for a year after the event, so that you can refer back to all of the practical nuggets when you’re grappling with your executive pay decisions, disclosures and engagements. Register today online! You can also contact us at info@CCRcorp.com or by calling 1-800-737-1271.
The question of who should lead the board can be a sensitive topic to weigh in on. Although it depends on the company and circumstances, it can help to know what others are doing. According to a recent report from The Conference Board – in collaboration with ESGAUGE, KMPG, Russell Reynolds and the University of Delaware – an increasing number of companies have separated the CEO and chair roles since 2020, but it is still a less common approach than “CEO duality” – especially among the largest companies.
The report assessed board leadership structures in the S&P 500 and Russell 3000. Here are other key takeaways:
• Large-cap companies are more likely to have a combined CEO/chair. In 2025, the current CEO served as chair at 42% of S&P 500 companies, compared with 34% in the Russell 3000.
• Incoming CEOs are rarely elected board chair at the time of transition. In 2025, 3 of 65 CEO successions in the S&P 500 (4.6%) and 9 of 353 in the Russell 3000 (2.5%) involved the CEO being named board chair at the same time.
• Most companies disclose a policy that preserves board discretion. In 2025, 79% of S&P 500 companies and 71% of Russell 3000 companies disclosed policies giving the board flexibility to separate or combine the roles depending on circumstances.
• Disclosed rationales for leadership structure are evolving. For role separation, the most commonly disclosed rationale remains that the two positions have different responsibilities. For role combination, references to improved communication and strategic execution have increased, while mentions that the CEO is best suited to set the board agenda have declined.
• Proxy advisors and large institutional investors typically focus on independent board leadership (independent chair or strong lead independent director) and evaluate proposals to separate the chair and CEO roles case by case.
Note that these stats can differ a bit depending on the measurement date and method – for example, this Freshfields proxy season writeup says 42% of S&P 500 companies have an independent board chair. Additionally, board leadership structures aren’t as neatly binary as the headline stats imply. For example:
– The TCB report shows that the boards of nearly 20% of S&P 500 companies are chaired by a non-independent director other than the CEO
– The Freshfields report breaks this down into 13% having an “executive chair” and 7% having an “other non-independent chair”
All that to say, if you’re benchmarking, you’ll probably want to use more than one source to inform your analysis and get a sense of the trend line. The TCB report offers these concluding thoughts:
CEO/chair structure remains an area where expectations are shaped by governance or sector context rather than a single market standard. Looking ahead, boards can strengthen confidence in their approach by reassessing the leadership model as circumstances evolve (including through the board’s regular performance evaluation process and during CEO transitions), clearly defining independent leadership authorities (independent chair or lead independent director), and ensuring that proxy disclosures explains how the structure supports board oversight, decision-making, and accountability.